Navigate Cost Squeeze And Tepid Demand: CRISIL’s Sethi On What Lies Ahead
- By Sharad Matade
- December 23, 2024
India’s tyre industry is bracing for a tough fiscal year, weighed down by sluggish demand, volatile raw material prices and muted export growth. Revenue is forecast to expand just 7-8 percent – supported by modest price hikes and a marginal rise in volumes – marking a second straight year of single-digit growth. However, operating margins are set to contract sharply as natural rubber prices remain elevated despite recent moderation. In a wide-ranging discussion, Anuj Sethi, Senior Director at CRISIL Ratings, unpacks the factors shaping the sector, from price pressures and replacement demand to global headwinds and evolving trade dynamics.
How would you characterise the current fiscal year for the Indian tyre industry, considering its challenges and opportunities?
With volume expected to grow just by about 3-4 percent due to sluggish demand, overall revenue growth will remain in single digit for the second straight year, this fiscal. On the other hand, high raw material prices, especially of natural rubber, rose sharply over the past 12 months and have only recently begun to moderate. To a moderate extent, tyre manufacturers are increasing tyre prices in the replacement market to offset the impact of higher input prices, albeit operating profitability will still be impacted this fiscal.
The report mentions 7-8 percent revenue growth this fiscal year, supported by a 3-4 percent increase in realisations and volume. What specific factors could push growth beyond this forecast, and what risks might undercut it?
While realisation growth due to price hikes being undertaken by tyre manufacturers is a certain given sharp increase in natural rubber prices, higher than projected volume growth could take the growth higher than expected. With about 2/3rd of the domestic demand
coming from replacement segment, and it being the primary volume driver, any significant decline in that demand can impact the growth forecast other way.
Given that replacement demand is the primary volume driver, how do you assess the longevity of this demand surge in the context of evolving consumer preferences and vehicle usage patterns?
The replacement demand is expected to sustain over the medium term driven by the strong automotive sales achieved in previous fiscals.
With operating profitability projected to drop 300 basis points, what contingency measures are tyre makers considering beyond gradual price increases to mitigate this impact?
The price of natural rubber, which constitutes about half of the raw materials, continued to surge sharply in the first half of fiscal 2025. However, ability to pass on this increase is limited due to modest volume growth. Small price hikes and continued focus at improving operating efficiencies on an ongoing basis is another way to offset the impact to some extent.
Natural rubber prices have been highly volatile, reaching record highs and then falling to around INR 170 per kg. What is your outlook for natural rubber prices in the near to medium term, and what factors will likely influence their movement?
The sharp rise in natural rubber prices is due to a global shortage caused by inclement weather in major producing countries such as Thailand and Vietnam, which account for about half of the global production. Going forward, increase in supply with improving hectarage and slowdown in global economies is likely to drive correction in international rubber prices. In the last couple of months, some moderation in natural rubber prices has happened.
China has a surplus in crude oil-derived raw materials, including carbon black and other chemicals. Do you anticipate this surplus impacting global prices for these commodities, and how might Indian tyre makers benefit or face challenges as a result?
Share of natural rubber in tyre manufacturing is 47 percent, while carbon black accounts for ~20-22 percent. Should carbon black prices remain under control, it will benefit domestic tyre manufacturers.
Export growth is expected to remain muted at 2-3 percent. How does the current geopolitical climate, including sanctions or trade restrictions, further complicate Indian tyre makers’ access to markets in North America and Europe?
Export growth is expected to remain sluggish due to challenging business conditions in US and Europe. However, certain segments like off-the-road tyres are beginning to see better prospects as stocks with dealers are moderating. This could help players with presence in the off-the road- tyre segment.
Exports to key markets such as North America and Europe are under pressure due to economic challenges and unviable operating costs, leading to plant shutdowns in regions like US, Europe and Israel. Is the Indian tyre industry at risk of facing similar challenges, or does it have structural advantages that mitigate these risks?
Indian players are better placed compared to some of the western peers due to comparatively lower cost of operations, though operating profitability has come under pressure this fiscal because of higher imported rubber prices. Also, Indian players have flexibility to supply in small batch sizes unlike Chinese peers, and hence this also works to their advantage, more prominently in higher margin segments such as off-the road tyres.
Have tyre makers explored new international markets or alternative trade routes to counter supply chain disruptions and higher freight costs?
Not really; to circumvent the difficult environment around the Suez Canal, vessels are going around the Cape of Good Hope, adding 2-3 weeks and additional freight cost on exports. Some of the costs are being shared with the customers.
The report references Extended Producer Responsibility (EPR) regulations. How significant is the financial and operational burden of compliance for tyre makers, and what progress has been made in addressing this?
Adoption of EPR regulations is not expected to have a very sizeable impact on profitability, though it will lead to investments in strengthening processes and in technology.
ATMA Seeks Duty-Free Natural Rubber Import Quota As Prices Reach INR 300 Per Kilogram
- By MT Bureau
- November 12, 2026
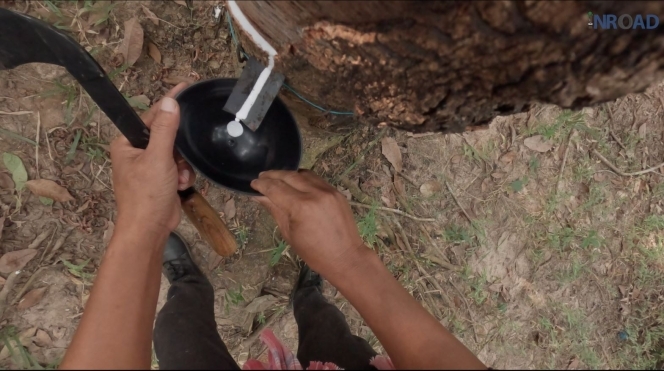
The Automotive Tyre Manufacturers’ Association (ATMA), the apex body representing tyre companies in India, has requested the Government of India to allow temporary duty-free imports of natural rubber under a Tariff Rate Quota (TRQ) mechanism.
The request follows an increase in domestic natural rubber prices to INR 300 per kg, representing a rise of nearly 62 percent from the November 2025 average of INR 186 per kg, alongside supply shortages during the peak production season.
In a letter submitted to Union Commerce and Industry Minister Piyush Goyal, the association proposed limiting the duty-free import quota to the assessed deficit between domestic demand and supply until market conditions stabilise.
During FY2025-26, India produced 905,000 tonnes of natural rubber against a consumption volume of 1.42 million tonnes, creating a supply gap of nearly 37 percent. Tyre manufacturers are simultaneously managing cost increases in synthetic rubber, carbon black, petroleum-based inputs and freight expenses driven by crude oil price movements linked to events in West Asia.
India's tyre industry generates an annual turnover of approximately INR 1,000 billion and exports exceeding INR 270 billion, having recorded 16 percent YoY export growth in Q1 of FY2026-27.
Arun Mammen, Chairman of ATMA, said, “Tyre manufacturers rely on the peak tapping season to secure domestic rubber for their production schedules. This year, supplies are falling short even during these months, while procurement costs have risen sharply. A temporary duty-free quota, limited to the assessed shortfall, would help manufacturers maintain production while protecting the interests of domestic rubber growers.”
Mark Stewart Steps Down As Goodyear CEO; Roger Wood Takes Interim Reins
- By TT News
- November 09, 2026
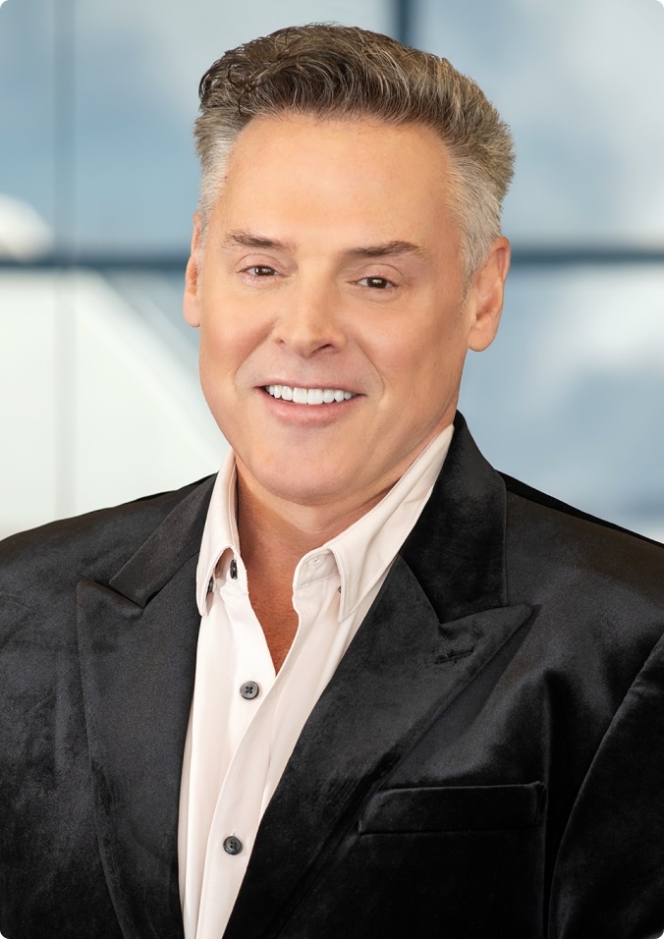
The Goodyear Tire & Rubber Company has announced that Mark Stewart has stepped down from his roles as Chief Executive Officer and President of the company and has also left its board of directors, effective immediately. In his place, the company has installed board member Roger Wood as interim Chief Executive Officer, with Wood leading the tyre maker while a leading executive search firm helps the board identify a permanent successor.
Wood joined the board in 2023 and has spent over 30 years leading businesses in the automotive and manufacturing sectors. He was previously Co-Chief Executive of Tenneco Inc., which designs, manufactures and distributes clean air, powertrain and ride performance systems worldwide for vehicle manufacturers and the aftermarket, and he holds board seats at PHINIA Incorporated and Brunswick Corporation. As part of taking the interim role, he has given up chairing the board's human capital and compensation committee.
Earlier this year, the board set up a special committee to scrutinise the company's businesses and operations, seeking ways to lift performance and deliver more value to shareholders. Directors and management are pursuing that effort through a wide-ranging assessment of strategic and operational options, among them refining the business mix and footprint, sharpening efficiency and funding new products and capabilities that underpin long-term growth. No further updates are planned unless and until the board concludes that more disclosure is warranted or required.
In a separate announcement dated 27 October 2026, Goodyear said Jerome Rouquet will become Executive Vice President and Chief Financial Officer on 1 December 2026. Rouquet, now Chief Financial Officer at Visteon Corporation and formerly a senior finance executive at Tenneco and Federal-Mogul, takes over from interim Chief Financial Officer Scott Deakin, who will help ensure a smooth handover.
Joe Hinrichs, Goodyear Board of Directors Chair, said, "Goodyear has made meaningful progress in becoming a more efficient and focused company, and the board believes this is the right moment to transition leadership to accelerate that progress and capture additional opportunity. Roger brings extensive automotive and industrial CEO experience, deep operational expertise and strong relationships across OEMs and aftermarket customers. He knows Goodyear, understands the opportunities ahead and has the board's full confidence to bring heightened focus and urgency to execution while we conduct a thorough search for a permanent CEO. We thank Mark for his contributions to Goodyear.
"The board formed a special committee earlier this year to conduct a rigorous strategic review of the company to help strengthen performance and create shareholder value. The board, together with the Enterprise Transformation Office, is evaluating a broad range of strategic and operational opportunities, and we are committed to taking the right actions to position Goodyear for stronger performance and long-term success. We look forward to providing an update as this work progresses."
Wood said, "Goodyear has iconic brands, talented people and significant opportunities to improve performance and deliver long-term value. As I step into this role, my immediate priorities are to support our associates and customers, sharpen execution and build on the work already underway to advance Goodyear's transformation. I look forward to working closely with the board, leadership team and the Enterprise Transformation Office to advance the strategic review and translate that work into actions that strengthen performance and position Goodyear for long-term success."
Michelin Appoints Terry Redmile As Chief People Officer For North America
- By TT News
- November 07, 2026
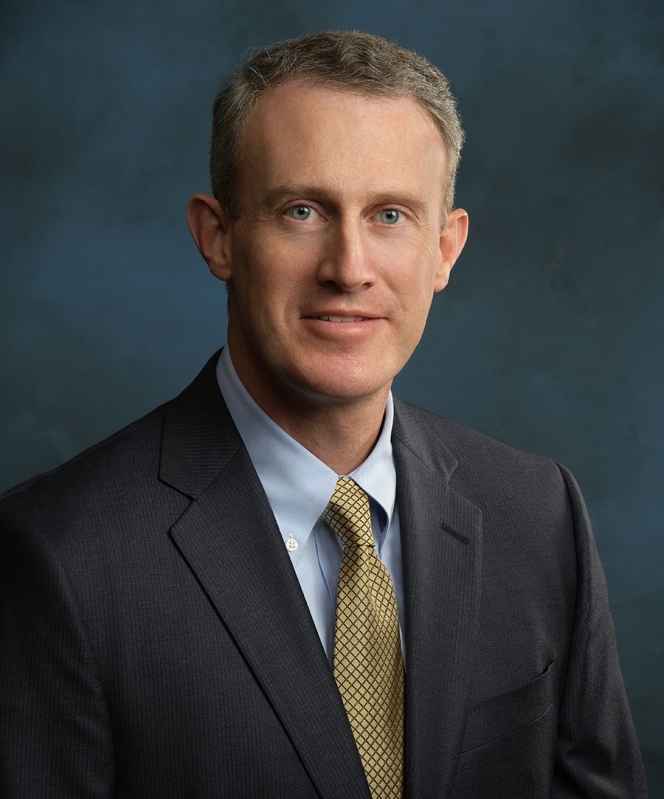
Michelin Group has appointed Terry Redmile as Chief People Officer for Michelin North America, Inc. In his new capacity, he will direct employee-focused operations throughout the North America Region, encompassing the recruitment, growth and retention of leading talent. His appointment places a seasoned internal leader at the helm of the company's people strategy.
A veteran of over three decades with Michelin, Redmile started as a co-op student at the firm's Greenville research and development centre. His tenure has spanned roles such as quality engineer and site director at the Fort Wayne, Indiana, manufacturing plant, culminating most recently in his position as senior vice president of manufacturing operations for the Americas. He also holds an MBA from Clemson University and a mechanical engineering bachelor's degree from the Georgia Institute of Technology.
Matthew Cabe, President and CEO, Michelin North America, Inc., said, “Terry understands our business, but more importantly, he understands our employees. His foundation in manufacturing and engineering gives him a firsthand understanding of where so many of our employees work every day and what they need to succeed. That perspective will be invaluable in this role.”
Redmile said, “The strength of Michelin has always been rooted in the strength of our talented teams. I’ve had the privilege of working alongside employees across our operations, and they are at the heart of what drives us forward. I want to build on that foundation and help our people continue to learn, innovate and shape what comes next for our industry.”
Apollo Tyres Announces INR 2.92 Billion Net Profit For Q2 FY2027, Appoints Ravi Kumar Shingari As CFO
- By TT News
- November 05, 2026
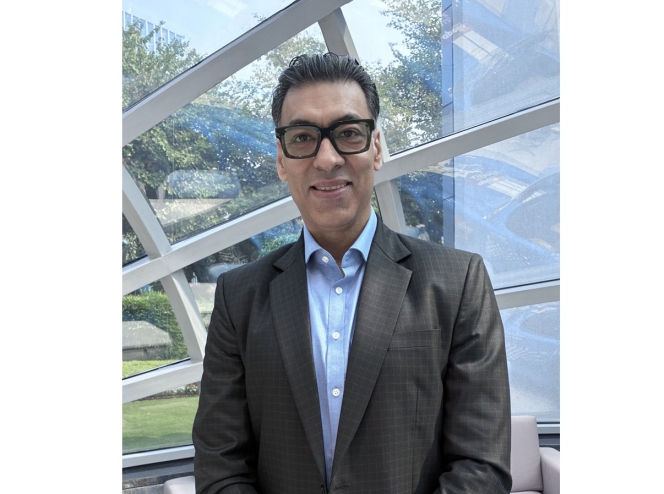
Apollo Tyres, one of the leading manufacturers of tyres in India, has reported its financial results for Q2 FY2027 and H1 FY2027, alongside announcing the appointment of Ravi Kumar Shingari as its new Chief Financial Officer, effective 4 November 2026.
In his new role, Shingari will be reporting directly to Vice-Chairman and Managing Director Neeraj Kanwar. He joined Apollo Tyres in 2018 as Group Head of Finance and subsequently managed functions across budgeting, accounts, investor relations, and legal affairs, following a 16-year tenure at KPMG as Partner in Tax and Regulatory.
The company announced that its consolidated revenue from operations for Q2 grew by 17 percent YoY to INR 79.68 billion, compared to INR 68.31 billion in the corresponding period of the previous fiscal year.
Operating profit for the quarter stood at INR 8.55 billion, while net profit grew 13 percent to INR 2.92 billion, as against INR 2.58 billion in Q2 FY26. The net profit figures include an estimated pre-tax restructuring cost of INR 260 million recorded as an exceptional item.
For H1 FY2027, revenue reached INR 153.66 billion, up 15 percent from INR 133.92 billion in H1 FY26, with operating profit closing at INR 17.23 billion and net profit at INR 6.41 billion.
Onkar Kanwar, Chairman, Apollo Tyres, said, "Growth across categories in India has been supported by our sustained rural expansion efforts and strategic association with cricket. In addition, the launch of new products in the commercial vehicle segment in India has strengthened performance during the past quarter. At the same time, geopolitical tensions in West Asia remain a headwind, resulting in elevated input costs and supply chain disruptions."
Also read: Apollo Tyres Appoints Abhineet Kothari As India Business Head For Vredestein
Comments (0)
ADD COMMENT