Challenges That Hinder Progress
- By Gaurav Nandi
- August 26, 2025
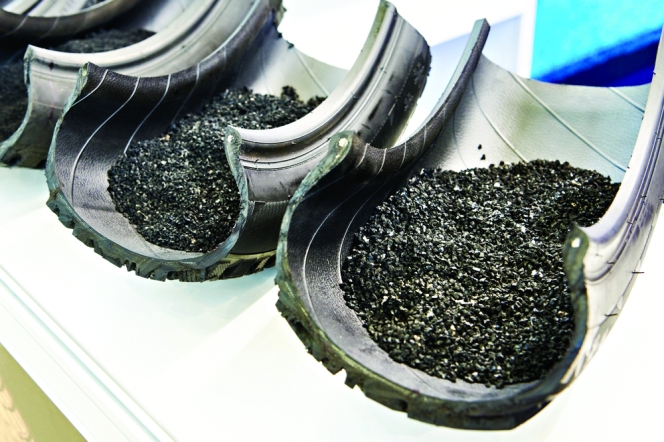
Despite two decades of reform, Europe’s tyre recycling ecosystem remains mired in regulatory inertia and market fragmentation. While the EU successfully curbed tyre landfilling in the early 2000s and achieved high collection rates, true circularity remains elusive. Over half of collected tyres are still incinerated rather than recycled into new products. The lack of mandatory recycled content targets, harmonised end-of-waste criteria and coherent eco-design regulations continue to stall progress. As environmental stakes rise and end-markets like artificial turf face bans, EuRIC’s latest manifesto lays bare the urgent need for systemic reform, spotlighting persistent policy voids, legal ambiguities and missed opportunities across the value chain.
Europe’s tyre recycling challenges have been building for over two decades. Back in 1999, the European Union banned tyre landfilling under Directive 1999/31/EC. This forced a major shift, and by 2003, landfilling tyres was officially prohibited. At that point, Europe still struggled to manage the sheer volume of end-of-life tyres (ELTs), often resorting to incineration or exporting them for disposal elsewhere.
Since then, collection rates improved dramatically, from around 25 percent in the mid-1990s to nearly 95 percent by 2010, but recycling quality remained substandard. Although most ELTs were collected, half were used for energy recovery, not material recycling. True circular solutions like reusing rubber in new tyres have lagged due to technological and regulatory hurdles
Complex EU regulations, limited mandates on recycled content and ecological concerns slow innovation. Over the past few years, initiatives like Life Green Vulcan, BlackCycle and policy push from the European Recycling Industries’ Confederation (EuRIC) show growing momentum, but real impact is yet to be seen.
EuRIC has been constantly advocating reforms that would change the course of the continent’s tyre recycling space with its recent manifesto delving into the immediate steps that ought to be undertaken to strengthen the tyre recycling industry.
EuRIC, through its Mechanical Tyres Recycling Branch (MTR), outlined a comprehensive vision for strengthening Europe’s tyre recycling sector. With over five million tonnes of tyres produced annually in the EU and around three million tonnes becoming ELTs, only about half are recycled – the rest are incinerated. EuRIC underscores the environmental advantages of mechanical tyre recycling and advocates for prioritising it over energy recovery to align with circular economy goals.
Speaking to Tyre Trends on the biggest obstacles to implementing mandatory recycled rubber content targets in new tyres and how industry collaboration can help overcome them, EuRIC’s Technical Advisor for tyres, Gabriel Gomez, mentioned, “Currently, the main regulatory challenge is the lack of a mandate from the authorities to define how and when the mandatory recycled content targets are to be implemented. We have received good feedback from the manufacturers in Europe regarding their willingness to include these targets. However, there is a need for a solidly defined regulatory framework that guarantees a level playing field in the tyre value chain and promotes innovation in this area.”
 “The main risk of failing to implement harmonised end-of-waste criteria lies in the growing, practical need for a defined set of criteria to determine end-of-waste status. If the EU delays further in the creation of harmonised end-of-waste criteria, this will push member states to create their own national criteria, which could vary significantly and prove incompatible. This fragmentation would lead to market disruption, create confusion across the value chain and introduce legal uncertainty – all of which would ultimately weaken the European recycling industry and its competitiveness,” he added.
He noted that EuRIC strongly supports a complete ban on the export of tyres and tyre shreds for incineration or landfilling. These practices represent a misuse of valuable resources that should be reintegrated into the economy and clearly contradict the waste hierarchy in the European Waste Framework Directive.
“EuRIC, representing Europe’s tyre recyclers would welcome swift implementation of such a ban, especially since existing tools such as the Waste Shipment Regulation are already being used to prevent exports to operators and facilities that do not ensure environmentally sound treatment of these materials,” noted Gomez.
THE MANIFESTO
The recently published manifesto by EuRIC proposes five key policy actions to address systemic barriers and unlock the potential of tyre recycling. First, it calls for mandatory recycled content targets – 10 percent for new tyres and 20 percent for automotive parts – to stimulate demand and reduce reliance on virgin rubber. Public procurement and financial incentives like VAT reductions are also suggested to support this demand shift. Currently, artificial turf accounts for a major share of ELT-derived rubber, but impending bans on micro-plastics threaten this end-market, making policy support more critical.
Second, EuRIC demands a ban on the export of unprocessed and shredded waste tyres outside the EU. ELTs are often exported to regions with weak environmental controls, where they are landfilled or incinerated. Countries like India have become significant importers, raising environmental and regulatory concerns. To counter this, EuRIC stresses the need for strict enforcement of the EU’s Waste Shipment Regulation and advocates for EU-wide end-of-waste (EoW) criteria to facilitate trade within the EU and promote high-value recycling.
Thirdly, the manifesto emphasises the importance of eco-design in tyres, urging that tyres be made retreadable, recyclable and free from hazardous substances. Innovations like self-sealing and noise-reducing foams, while performance-enhancing, impede recycling and can even cause fires during shredding. EuRIC supports the Ecodesign for Sustainable Products Regulation (ESPR) and wants tyre manufacturers to bear the cost of non-recyclable designs.
Fourth, EuRIC promotes the Digital Product Passport (DPP) as a key enabler of recycling efficiency. Current data on tyres is insufficient; hence, they propose leveraging RFID technology to track chemical composition and recyclability through a centralised database. This transparency would help recyclers better handle materials and comply with chemical regulations.
Lastly, the manifesto addresses the need for a science-based chemicals policy that supports recycling rather than undermining it. The current trend towards hazard-based regulation with near-zero thresholds for certain chemicals risks sidelining recycled materials. EuRIC urges a shift towards risk-based assessments, transparent
testing methods and harmonised standards to ensure recycled materials remain viable in the EU’s green transition.
TOWARDS RECYCLABILITY
According to Gomez, mechanical tyre recycling is a recycling method for rubber that has stood the test of time. It remains the most common and best-established route for recycling tyres in Europe with the technology offering high-quality output. It also has the added value that it can serve as a reliable supplier for further processing technologies dealing with vulcanised rubber. Recycled rubber from ELTs offers significant potential for technologies that require a uniform and predictable input to maintain control over industrial processes.
Nonetheless, over three years after rubber from ELTs was prioritised, no regulation has materialised yet. Commenting on what lead to the stalling, Gomez noted, “The past year has brought major changes at EU level with the start of a new Commission mandate, which may explain the shift in priorities. However, at EuRIC we are working closely with manufactures and policymakers to keep the issue high on the agenda. We see harmonised EoW criteria as a key opportunity to align the interests of recyclers and manufacturers. Harmonised EoW criteria would bring significant benefits for the entire value chain, from boosting investment and legal certainty to increasing the uptake of recycled materials.”
Alluding to whether the current EU chemicals legislation, especially restrictions on substances like PAHs, appropriately balances environmental protection with the needs of a circular economy or does it unintentionally favour virgin materials, he stated, “It is not a matter of favouring virgin materials. The main issue is that the current legislation is not designed to consider that the materials in an article may have more than one life. Whenever the legislation targets the content of a substance in a recycled material, sometimes it fails to consider the real exposure to the substance based on the application and the nature of the material.”
Digital Product Passport is another vital tool for the entire industry’s circularity goals. While it is still in its early stages, EuRIC notes that there are projects that target the implementation of the DPP in tyres and it is optimistic about the possibilities this tool offers to the industry. Amongst the information that the DPP should make available for recyclers is the contents of substances of concern and hazardous substances as well as any substances or features that would hinder the recycling of the tyres. With this information in hand, the recyclers will be able to sort the tyres in a manner that allows for safer recycled products and more efficient processing.
PERSISTENT HURDLES
According to Gomez, illegal or poorly regulated exports of tyres create serious problems both economically and environmentally. They drain valuable raw materials from the EU and risk harming the environment and public health in importing countries if ELTs are not treated in an environmentally sound manner.
Furthermore, the loss goes beyond the economic aspect when it comes to the materials used on tyres. Incinerating ELTs destroys a valuable resource like rubber and locks us into a linear economy model that’s no longer fit for purpose. Recycling, on the other hand, and overall circularity of tyres, keeps materials in the loop, boosts resilience and contributes to EU sustainability and competitiveness.
A strong starting point to combat illegal exports would be the rigorous enforcement of the Waste Shipment Regulation, specifically targeting ELT exports. If recyclers can count on a steady, reliable supply of materials, they will invest. Increased availability of material and supply security are essential to encourage investments in recycling.
“An important take-away of the policy related to tyre recycling is that tyres should be treated as strategic resources, not just waste. Tyres are essential to every economy activity and inevitably reach its end-of-life stage. This makes it critical to regulate the full lifecycle, from design to disposal, with circularity in mind. Aligning on principles, like prioritising recycling over landfilling or incineration, would already be a big step forward globally,” averred Gomez.
Commenting whether Europe’s mechanical recycling infrastructure is equipped to handle a sharp increase in ELTs if exports are banned, he mentioned, “The mechanical tyre recyclers in Europe are determined to meet the challenge and tackle the increase in ELTs if an export ban is implemented. However, unlocking further capacity and investments in future development projects depend on regulatory certainty. That means a guaranteed level playing field through harmonised EoW criteria, recycled content targets and eco-design for improved recyclability. With the right framework and tools, uncertainty can be removed and investments will follow.”
While the mandatory recycled content requirements are essential to boost recycling, complementary short-term financial incentives, whether market-based or fiscal, are equally necessary to close the price gap between primary and recycled materials. Fiscal incentives, such as reduced VAT rates for recycled materials and products made from recycled materials, can play a major role in encouraging uptake. Green public procurement also holds substantial potential to stimulate demand for more sustainable and circular products.
Recycled materials from ELTs have real potential in the EV supply chain. Interest is growing, and EuRIC is confident that recycled rubber can be a reliable, high-quality material to support the shift to greener mobility.
Gomez noted that there are many encouraging examples of manufacturers incorporating recycled and sustainable materials into tyre design. A great advantage that recycled materials from ELTs offer is the availability of high-quality recycled raw materials that reliably allow manufacturers to experiment and innovate as they know that the recycling industry is capable and ready to deliver.
Kraton To Raise Polymer Prices In North America Starting December 2026
- By TT News
- November 07, 2026
Kraton Corporation, a leading global producer of speciality polymers and high-value bio-based chemicals derived from pine wood pulping co-products, has announced a price increase of USD 220 per metric tonne, equivalent to USD 0.10 per pound, across all polymer products sold in North America. The affected lines include Kraton D SBS, Kraton D SIS and Kraton G SEBS/SEPS.
According to the company, the adjustment is necessary to offset significant and sustained increases in feedstocks, energy, logistics, process materials and other manufacturing costs. The increase will take effect on 1 December 2026 or as permitted by applicable contracts.
Evonik Strengthens Global Silicone Network With Essen Expansion
- By TT News
- November 04, 2026
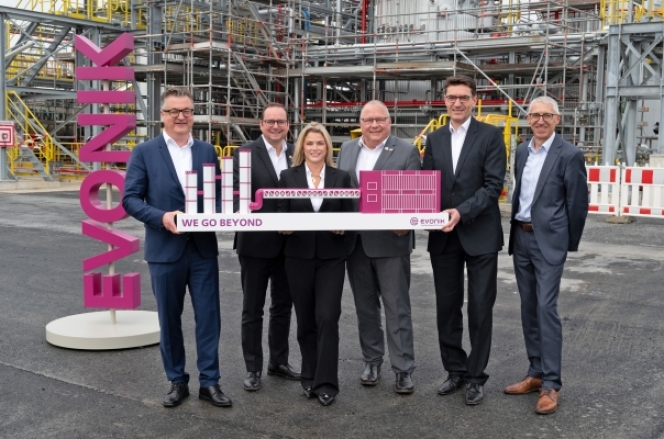
Evonik, a global speciality chemicals company, has completed a EUR 52 million expansion of its silicone platform at the Essen Goldschmidtstrasse site in Germany, constructing a new production plant and a large tank farm. The facility raises output capacity for organomodified silicones, a core product group in the company’s global silicone network.
The Essen site operates as a central node in that network, closely tied to Evonik facilities in Geesthacht, Obernburg and Wittenburg in Germany, Pandino in Italy, Shanghai in China and Hopewell, Virginia, in the United States. The expansion strengthens the resilience of this international production system by lessening the need to ship intermediates and finished goods between locations.
Logistics infrastructure has been optimised to support more efficient operations. A new 150-metre pipe bridge links four production units and 15 manufacturing assets to the tank farm, which comprises five stainless-steel tanks, the tallest standing 24 metere and holding substantial quantities of key raw materials. The result is steadier production, more robust supply chains and reduced reliance on short-term deliveries. The tank farm has enlarged the Essen site from 32 to 35 hectares.
The project was executed with the site fully operational and despite constrained space, drawing on roughly 80 Evonik employees and over 230 contractors from 25 partner companies. Essen Goldschmidtstrasse also features in Evonik’s newly developed long-term plans, which assign a clear profile to each of six major production sites – Essen Goldschmidtstrasse, Marl, Wesseling, Darmstadt/Weiterstadt, Rheinfelden and Hanau – as guidelines for future development. Under this framework, Essen Goldschmidtstrasse is positioned as a centre of excellence for customer-specific formulations.
Lauren Kjeldsen, the Evonik Management Board member responsible for the Custom Solutions segment, to which the business belongs, said, “This expansion strengthens our silicone production platform, enhancing supply chain resilience and creating a strong foundation for profitable growth. This latest investment highlights the important role that our innovative German sites play in the success of our global operations.”
Roberto VilaKeller, head of the responsible Business Line Interface & Polyurethane Additives, said, “The investment in Essen strengthens our global production network and further enhances our ability to serve customers reliably around the world. It significantly expands our production capabilities, reduces potential bottlenecks and creates opportunities for future growth in attractive markets.”
Thomas Kufen, Mayor of Essen, said, “At a time when industrial investment is more important than ever, projects of this scale send a strong signal for Essen’s economy and the wider region. They secure high-quality jobs, strengthen competitiveness and demonstrate the international attractiveness of our city as an industrial hub.”
- Association of Natural Rubber Producing Countries
- ANRPC
- Natural Rubber
- Monthly NR Statistical Report
ANRPC Publishes Monthly NR Statistical Report For September 2026
- By TT News
- October 31, 2026
The Association of Natural Rubber Producing Countries (ANRPC) has published its Monthly Natural Rubber Statistical Report for September 2026, a month marked by broad-based price gains. Firm fundamentals, constrained supply and steady downstream demand combined with geopolitical and macroeconomic uncertainty to lift prices. Renewed Middle East conflict and disruptions to major shipping routes weighed on sentiment, while energy markets were especially affected by the closure of the Strait of Hormuz and attacks on transiting vessels, which raised risks to global energy supplies and strengthened the crude oil risk premium.
According to the report, physical prices for most major grades advanced. SMR-20 in Kuala Lumpur averaged USD 2.50/kg, up 7.96 percent month-on-month, and STR-20 in Bangkok rose 5.80 percent to USD 2.53/kg. RSS-3 in Bangkok slipped 0.30 percent to USD 2.79/kg, while RSS-4 in Kottayam eased 1.39 percent to USD 2.88/kg. Latex-in-bulk in Malaysia gained 3.60 percent to average USD 1.79/kg. Cautious tyre-manufacturer purchasing, limited to immediate needs after earlier increases, weighed on the RSS market. Latex drew support from tight supply, as persistent rainfall disrupted tapping and limited fresh and concentrated latex availability, while glove, healthcare and industrial demand held stable.
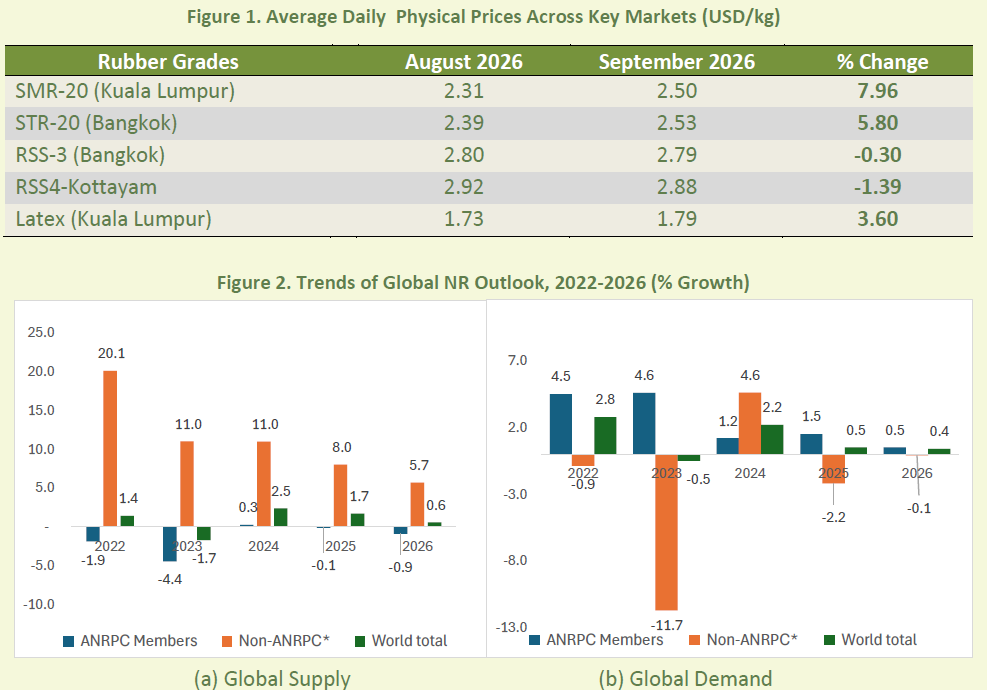
Trade flows diverged. China's imports grew 2.56 percent month-on-month, India's 11.36 percent and Malaysia's 17.85 percent, whereas Viet Nam's fell 3.40 percent. Exports rose 3.07 percent in Thailand, 7.30 percent in Malaysia and 1.91 percent in Cambodia, while Indonesia edged down 1.40 percent and Viet Nam recorded the steepest decline at 9.72 percent.
Global production is projected at 15.039 million tonnes in 2026, up 0.6 percent from 14.953 million tonnes in 2025, with September output estimated at 1.4 million tonnes. Uneven rainfall and elevated temperatures slowed supply recovery across Southeast Asia. Global demand is forecast to rise 0.4 percent to 15.356 million tonnes from 15.301 million tonnes, with the largest volume increases among ANRPC member countries. Prospects depend on vehicle sales, tyre production, shipping conditions and weather-related disruptions, while expanding electric-vehicle markets in China, India and Europe support modest growth.
The ringgit traded between RM4.04 and RM4.10 per US dollar, and the baht between THB 32.89 and 33.55. The SHFE January 2027 contract averaged CNY 19,070/tonne, up 5.3 percent month-on-month, and the SGX December 2026 contract averaged USD 2.41/kg, up 7.6 percent. Brent crude averaged USD 114.16 per barrel, a 25.3 percent monthly increase driven by geopolitical risks and shipping disruptions through the Strait of Hormuz.
- Birla Carbon
- Carbon Black
- Sustainable Carbonaceous Materials
- Sustainable Carbon Blacks
- International Rubber Conference
Birla Carbon To Showcase Electric Mobility-Focused Carbon Black Portfolio At IRC 2026
- By TT News
- October 28, 2026
Birla Carbon, a leading global supplier of carbon materials, will exhibit at the International Rubber Conference (IRC) 2026, scheduled for 2–6 November in Nagoya, Japan, at Booth B. The company aims to address application-specific demands arising from the shift towards electric mobility, which places greater emphasis on tyre wear and energy efficiency while requiring automotive rubber components to balance durability with ride comfort.
A Very High Structure (VHS) lineup awaits manufacturers of passenger car, light truck, truck and bus tyres. These grades were engineered to meet electrification requirements and tightening standards such as Euro 7, delivering gains in tread wear, energy efficiency and tyre longevity.
Sustainability also features prominently. The company's Continua Sustainable Carbonaceous Materials (SCM) and Sustainable Carbon Blacks (SCB) lines, which contain higher levels of recycled or bio-based material, are intended to help tyre makers pursue circularity targets. Their dependable quality and ability to be supplied at scale in large volumes make them viable for production use, and the Continua range carries ISCC PLUS certification.
Mechanical rubber goods round out the display. Grades aimed at bushings enhance mixing and dispersion, contributing to fatigue life and component durability, while formulations for mounts pair low hysteresis and low stiffness with reinforcement so that durable parts can be produced without sacrificing ride comfort. Drop-in grades for extrusion reduce defects, scrap and screen-pack changes while raising throughput and extending service life. Simulation and technical expertise help customers assess materials, and global production plus Asian capacity growth support long-term supply.
Amit Kumar, President – Asia, Birla Carbon, said, “Asia’s tyre and rubber manufacturers are shaping the next phase of mobility, and their material requirements are becoming increasingly stringent. As the clear leader in our industry, Birla Carbon aims to grow alongside our customers, combining application-focused innovation with dependable local supply. We see performance and circularity as priorities that must progress together. By expanding our capabilities in Asia and strengthening customer partnerships, we aim to help manufacturers meet evolving market needs and build greater long-term competitiveness.”
Comments (0)
ADD COMMENT