- Lanxess
- Lanxess India
- Vulkanox HS Scopeblue
- Matthias Zachert
- India Application Development Centre
- tyre
- rubber
Tyre Industry Continues To Be A Key Growth Driver For Lanxess India
- By Nilesh Wadhwa
- April 14, 2025
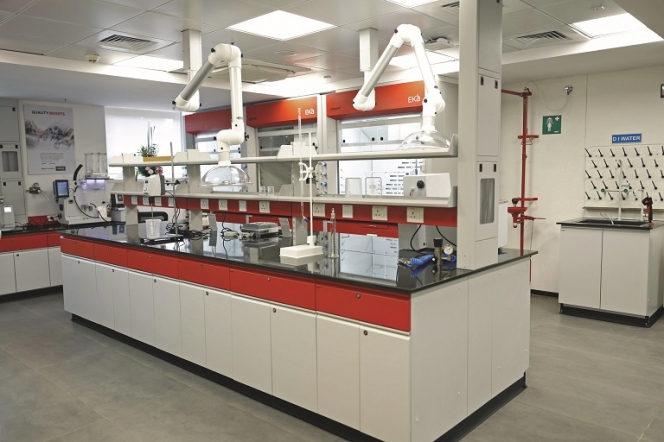
The German speciality chemicals company recently inaugurated the first India Application Development Centre (IADC) in the country’s financial capital, reinforcing its commitment and outlook for the country.
For Lanxess India, tyre industry accounts for almost 25 percent of its business, as against global average of around 10 percent. And the company’s management continues to be upbeat about the growth story for Indian tyre makers.
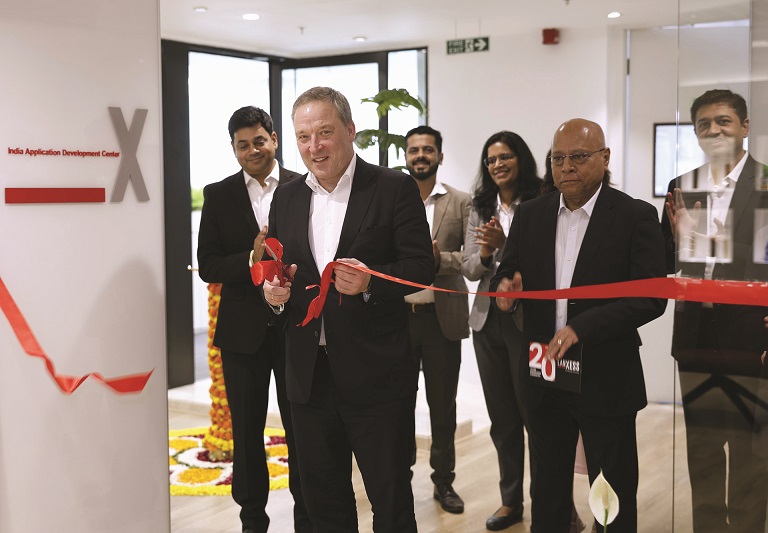
“India, from our point of view, will play a very important detrimental role (for Lanxess). Because when you want to grow your industry, which Prime Minister Narendra Modi clearly has as an ambition, you need the chemical industry and all their precursors. And if you want to help the Indian industry to further develop (new solutions), you need to have local application for local needs,” remarked Matthias Zachert, Chairman of the Board of Management of Lanxess.
He was speaking on the sidelines of the inauguration of the India Application Development Centre (IADC) in Thane, Mumbai, which also marks a significant commitment by the German chemical major for the country.
Lanxess is said to be the world’s largest supplier of rubber additives focusing on solutions around rubber chemicals, speciality chemicals and processing aids for the rubber industry. The company’s solutions find their way in high-performance rubber products such as tyres, treads, seals and even drive belts.
At present, Lanxess has established two production facilities in India – Jhagadia in Gujarat and Nagda in Madhya Pradesh. The tyre industry is primarily supported by Lanxess Rhein Chemie Additives Divisions, which manufactures Rhenogran and Rhenodiv at the Jhagadia facility. The company has invested over EUR 70 million in the Jhagadia facility, which not only supports the domestic customer base for Lanxess but also its customers in the Asia-Pacific region. The company has a longstanding presence in India, with representation from all 10 of its business units and a workforce of around 800 employees.
It comes as no surprise that Zachert sees India as a critical growth region for Lanxess, offering immense opportunities for collaboration and innovation.
INDIAN TYRE INDUSTRY A KEY GROWTH DRIVER
Globally, the automotive industry in particular is transitioning from being seen as a seller of products to a mobility solutions provider, what’s with new business models or service solutions.
Zachert sees that while the tyre market was consolidated for many years, it has started opening up in the last decade.
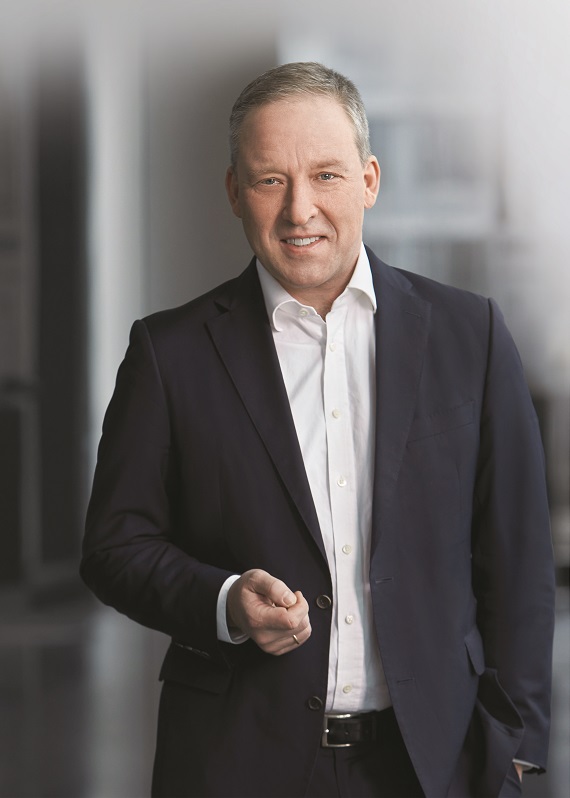
“The global tyre market has opened up, strongly driven by Chinese tyre manufacturers but also Indian tyre manufacturers. We have rising stars here in India. Mobility has always led to liberty and flexibility for mankind. This will be a trend that in the next 10-20 years is not going to vanish. Mobility will be important, which means the tyre industry is important. And therefore, I look positively at the tyre industry going forward, notably the one that is located here in India,” said an optimistic Zachert.
It is important to understand that the company has almost 25 percent of its business exposure to the Indian tyre segment, which could be amongst the highest for the company.
“For our group, the mobility exposure that we have worldwide as a company is 10 percent. We are over-proportionally present here in India, which is good and normal because the industry is expanding. The Indian tyre market is expanding not only locally but globally,” he said.
The recent setting up of IADC is part of Lanxess’ strategic focus on India as a key market and innovation hub. The strengthening of R&D will enable the company to enhance its ability to deliver high-value, specialised solutions tailored to local needs.
To begin with, the company has integrated expertise from two key businesses in India: Lubricant Additives (high-performance additives and additive systems, synthetic base fluids and ready-to-use lubricants) and Material Protection Products (antimicrobial, disinfection and preservation solutions). Going forward, the idea is to be present with all business units’ expertise at the IADC.
Namitesh Roy Choudhury, Vice-Chairman and Managing Director, Lanxess India, said, “By establishing the IADC, we are bringing our expertise closer to our Indian customers. This centre will not only support innovation but also strengthen our ability to address evolving market trends with speed and precision.”
For Lanxess India, the IADC aligns with its transformation journey towards a speciality chemicals company. The aim is to focus less on cyclical business areas and solutions for critical applications and move towards a partner for sustainable mobility or consumer protection. And the company sees India’s growing industrial base and expanding consumer markets as an ideal platform for driving such advancements.
SUPPORTING THE TYRE INDUSTRY
The production of the plain looking black tyre is more than just moulding of rubber; it is a complex process, which includes incorporating various raw materials and scientific steps to ensure that the tyres are built up to a particular specification. After all, tyres remain and are supposed to be the sole point of contact between a vehicle and the road when in motion.
Lanxess, for its part, supplies solutions across mixing, batch-off, extrusion & tread marking, tyre inspection & repair, tyre curing, green tyre spraying and tyre building processes.
According to the company, a durable car tyre is the result of a complex manufacturing process in which the tyre is built-up from various rubber compounds and reinforcing materials. It explains that by using rubber chemicals and various fillers, the raw material rubber is turned into a high-performance product. This is because rubber is soft and not very durable until vulcanisation. By selecting the type of rubber, the crosslinking chemicals and additives required for the desired technical properties of the end-product, high-performance products such as tyres and other rubber products are created.
EUROPEAN COMPANIES TO STEP OUT OF PETROCHEMICALS
The chemicals industry has undergone a sea of change, especially given the evolving trend from geography-focused development to globalisation. For the last few years, there has been a growing pressure, especially given the focus on sustainability.
To support the sustainability drive, the company recently introduced Vulkanox HS Scopeblue, a next-generation rubber additive designed to help tyre manufacturers produce more durable and environmentally friendly tyres. The anti–degradant effectively protects tyres from the damaging effects of oxygen and heat while offering reduced environmental impact. Its low volatility and minimal migration tendency further enhance tyre performance and longevity, making it an optimal solution for modern, eco-conscious manufacturing.
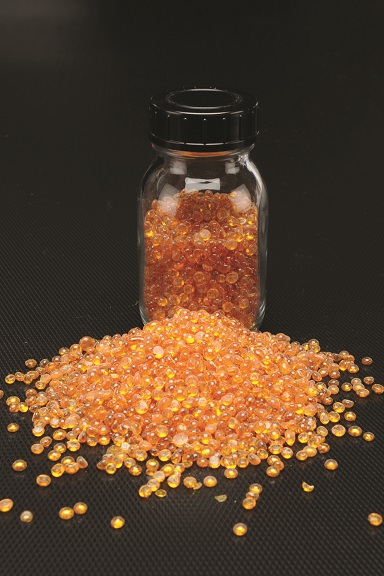 The company claims that the Vulkanox HS Scopeblue boasts a carbon footprint more than 30 percent lower than its conventionally produced counterpart thanks to the use of bio-circular acetone and renewable energy in its production process. It is being currently manufactured at an ISCC PLUS-certified plant in Germany; this mass-balanced additive retains the same chemical structure as the original product, allowing tyre manufacturers to adopt it seamlessly without altering their existing production processes.
Zachert further said, “Times lead to change. The industry dynamics of chemicals has been adjusting to change for the last decade and will continue to see changes for the next decades. If I look into the next 10 years of the chemical industry, my personal prognosis is that you will see that the European chemical companies will more and more step out of petrochemicals and go upstream. And this is happening as we speak. My thesis also is that the European industry will focus more on niche polymers and speciality chemicals. The upstream and volume polymers will go elsewhere, where you have the raw materials and cheap energy. Countries that are destined to dominate these kinds of chemicals over the next 10 years, is the Middle East and the United States. Europe used to be the epicentre of chemicals 20-30 years ago from polymers to chemicals to pharmaceuticals.”
Then there is the shift from global supply chain to more of regional supply chain given the geopolitical situation.
“I see that with the current world with geopolitical tensions, the likelihood is high that we will go back to trade zones. And therefore, the global value chain in chemicals is one where many companies will have to rethink the global approach and turn towards a more regional approach,” added Zachert.
Revyre Targets SBS Market With Tyre-Derived Polymer After Auckland Road Trial
- By Gaurav Nandi
- September 14, 2026
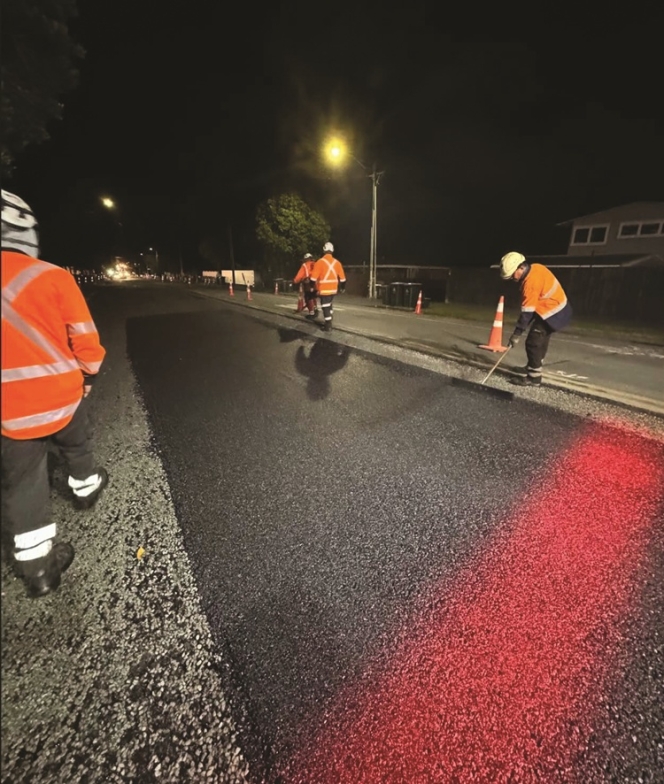
The company is betting that a polymer manufactured from end-of-life truck tyres can disrupt the market for petroleum-based styrene-butadiene-styrene (SBS), a widely used road-binding additive whose pricing and availability are tied to global oil markets. After completing a live road trial with Road Science and Auckland Transport in New Zealand, the company is preparing to use the results as a springboard for expansion into Australia and Sub-Saharan Africa, positioning the recycled material as a lower-cost, lower-carbon alternative to virgin polymers.
New Zealand-based Revyre Global Limited is positioning a polymer manufactured from end-of-life truck tyres as a lower-cost alternative to petroleum-based styrene-butadiene-styrene (SBS) after completing a live road trial with Road Science and Auckland Transport in New Zealand.
The company has spent several years developing the product as a direct replacement for SBS. Unlike conventional tyre-derived asphalt, which relies on crumb rubber, the company’s Chief Executive Officer Shaun Zukor told Tyre Trends that its proprietary thermomechanical process produces a remanufactured polymer with blending characteristics similar to SBS, allowing it to be used in existing asphalt infrastructure.
“Our primary objective was to develop a drop-in replacement for SBS, which is a petroleum-derived synthetic polymer,” Zukor said. “SBS is expensive, made from virgin materials and is widely used to improve road durability, fatigue resistance and overall pavement performance.”
The company began engaging Road Science, a division of Downer, and Auckland Transport after completing laboratory validation with engineering consultancy WSP in New Zealand.
Before approaching customers, it invested around 18 months in laboratory testing to validate the material’s performance.
Following successful laboratory trials, Road Science carried out its own evaluations before, together with Auckland Transport, deciding to trial the material on Blockhouse Bay Road, one of Auckland’s busiest roads.
The project then underwent another lengthy approval process involving Auckland Council and scientific advisers.
“It took another year to a year and a half to obtain all the necessary approvals from the council and its scientific advisors,” Zukor said. “They wanted to verify that all the claims in our technical literature were accurate.”
Construction of the trial road took place over three days in March and the company expects to receive the first performance data around September. Those results are expected to support commercialisation in overseas markets.
“Our business is focused only on New Zealand at the moment because we’re using it as a proof of concept,” Zukor said. “Once those results are available, we’ll publish them. That will place us in a much stronger position to take the product into Australia and Sub-Saharan Africa.”
The company estimates that entering Australia would take another 12 to 18 months after trial results are available and a planned New Zealand manufacturing facility becomes operational.
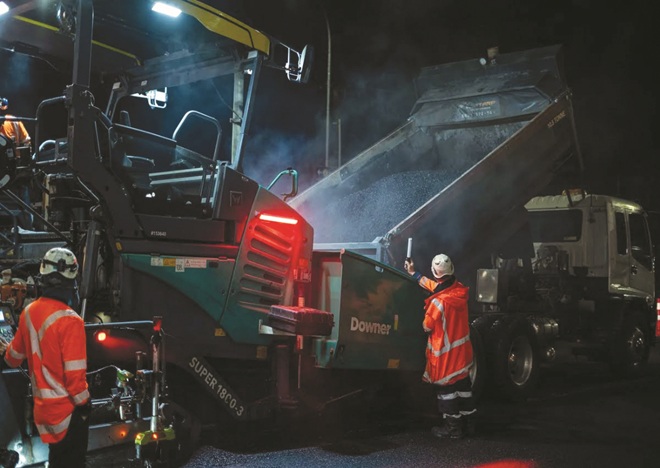
Although the current road project used only a small quantity of material because it is a demonstration, Zukor said the commercial opportunity could expand significantly.
“We used a relatively small amount of material for this particular project, but if the opportunity grows as expected, supplying the Auckland Transport network alone could eventually consume between 40–50 percent of our production capacity,” he noted.
MATERIAL ECONOMICS
The company currently manufactures the material primarily from truck and bus radial (TBR) tyres and earthmover tyres because of the higher natural rubber content.
While the SBS substitute represents the company’s immediate focus, it has divided its broader product portfolio into three categories. Revpol A, manufactured mainly from passenger and light truck tyres is intended for lower-performance rubber products such as rubber tiles, shoe soles and conveyor belts.
Revpol B targets asphalt applications and new tyre manufacturing, while Revpol C, produced largely from earthmover tyres, is designed for higher-performance applications.
The company is not currently manufacturing at its own facility but plans a new production unit in New Zealand. Until that facility is operational, product for trials is being supplied by its Canadian partner.
The technology relies primarily on a thermomechanical recycling process rather than chemical recycling. Whole tyres are broken down with steel separated from the rubber before the rubber is processed to a 30-mesh particle size and passed through Revyre’s proprietary thermomechanical process.
Zukor said only a very small amount of non-toxic, FDA-approved chemicals are used and that the process is driven primarily by operating parameters rather than chemical reactions.
He added that one of the key advantages of the technology is that it can be incorporated into existing SBS blending infrastructure with minimal changes as most development work focused on determining the optimum blending ratio rather than overcoming technical limitations.
“The primary technical challenges relate to the blending ratio,” he said, adding, “The higher the percentage of Revpol you add, the higher the temperatures and shear forces required in the bitumen blending terminals.”
Although the company has successfully blended as much as 20 percent Revpol into bitumen during development, Zukor said performance gains diminish beyond a certain point.
It has identified an optimum blend of between 5 percent and 10 percent depending on the application, ranging from conventional roads to heavy-duty pavements and airport runways.
“Any facility that currently blends SBS using its existing infrastructure can also blend our product using that same infrastructure,” he said.
CATALYST FOR SAVINGS
Zukor believes the material can reduce both costs and environmental impacts while improving pavement performance.
“We want to create a product that is environmentally sustainable, has an abundant raw material supply and is 20–40 percent cheaper than virgin materials while also having a significantly lower carbon footprint,” he stated.
Laboratory testing has produced encouraging results. According to Zukor, New Zealand’s wheel-tracking standard requires materials to withstand 800,000 load cycles, while Revyre’s product continued to perform until testing was halted at two million cycles.
“Our product achieved nearly two to three times the required wheel-tracking performance compared with standard bitumen,” he noted.
He also added that the objective is to produce road surfaces that are less expensive, more durable and environmentally sustainable while simultaneously addressing the challenge of managing end-of-life tyres.
“We believe this product ticks all of those boxes and have obtained a patent for it,” he said.
MANUFACTURING SCALABILITY
Although the company is currently relying on manufacturing capacity in Canada, Zukor said its modular production model could support significant expansion once commercial demand develops.
“We can currently produce up to 10,000 tonnes of this product, but because our production facilities are modular, capacity can easily be scaled anywhere from 1,000 tonnes to 50,000 tonnes, depending on market demand and the requirements of a particular region,” said Zukor.
Once the planned New Zealand facility becomes operational, Zukor expects its tyre feedstock to be supplied through Tirewise, the country’s extended producer responsibility (EPR) scheme for end-of-life tyres.
Under the programme, every imported tyre attracts a levy that funds incentives for registered collectors, processors and end users to move tyres through the approved recycling chain. Zukor said Revyre intends to register again as a processor after commissioning its new plant.
GOING PAST HURDLES
Zukor acknowledged that customer adoption remains the biggest hurdle. Road contractors also need to validate new formulations through laboratory testing before incorporating them into their pavement designs. Hence, Revyre is focusing on multinational contractors already operating in New Zealand to accelerate adoption, believing successful validation locally could support deployment elsewhere within those organisations.
He also believes global dependence on petroleum-derived SBS strengthens the case for tyre-derived alternatives.
“If you look at SBS, it’s already a product that’s in very high demand globally. Because it’s petroleum-based, its availability and pricing are heavily influenced by global macro-economic and geopolitical events,” Zukor said.
He said the company’s commercial proposition rests on three principles viz-a-viz consistent quality, supply and pricing.
According to Zukor, replacing virgin SBS with tyre-derived polymers could help localise supply chains, reduce exposure to petroleum price volatility and improve environmental outcomes while lowering costs for road owners.
Beyond New Zealand, Revyre is also evaluating opportunities in North America through its Canadian partner and is exploring future markets for tyre-derived materials.
Azur’s Blueprint For A Circular Tyre Industry
- By Gaurav Nandi
- September 11, 2026

Europe’s tyre industry stands at a crossroads as mounting regulatory pressure, resource constraints and circular economy targets reshape the end-of-life tyre landscape. Despite Germany achieving one of the world’s highest recycling rates, an estimated 100,000 tonnes of used tyres continue to leave the country annually, undermining domestic recovery efforts. In conversation with Tyre Trends, AZuR Network Coordinator Anna-Maria Guth outlines the policy reforms, recycling technologies, retreading opportunities and cross-border collaboration needed to keep valuable raw materials in circulation and build a fully circular European tyre ecosystem.
What gaps in the traditional tyre value chain led to the establishment of the AZuR network?
In Germany, we have a very high recycling rate for end-of-life tyres. However, following a merger of certified tyre disposal companies that collect and sort tyres, it became clear that we needed to bring all stakeholders together to really make progress. The excellent response to the AZuR network shows that this is the right approach.
The European tyre industry is under increasing pressure regarding emissions, waste management and the circular economy. What policy measures are still needed to accelerate the widespread adoption of tyre recycling?
Couple of policy implementations must be achieved in order to reach this goal. The first is a strict ban on the export of ELTs and rigorous enforcement of this regulation. Secondly, clear, predictable and statutory regulations regarding the use of ELT granulate. Lastly, consistent implementation of circular economy strategies.
 What role can recovered carbon black (rCB) play in reducing Europe’s dependence on primary fossil raw materials?
The pyrolysis companies in the AZuR network are making great strides in improving the quality of rCB. We are optimistic that in the foreseeable future, we will be able to produce a grade that allows the material to be incorporated into new tyres in larger quantities. That would be a major breakthrough and would create real added value as it would keep the raw materials within the circular economy.
How does AZuR distinguish between mechanical recycling, devulcanisation and pyrolysis in terms of sustainability and scalability?
Within the network, we adhere to the European waste hierarchy viz-a-viz prevention, reuse, recycle including mechanical and chemical and, finally, thermal recycling.
We are open to all technologies when it comes to processes. However, it is clear that in the interests of the circular economy, we want to minimise thermal recovery. And this also applies to pyrolysis oil provided it is not used for the production of new products but as a secondary fuel.
How close is the tyre industry to establishing tyres made with recycled materials without compromising on performance?
Some manufacturers are already field-testing tyres containing over 70 percent recycled and bio-based raw materials. The industry is very active in this area. However, we would like to see a more nuanced approach to recycled materials and bio-based materials.
Bio-based materials cannot be the solution in the medium term and the EUDR is already restricting the use of bio-based materials in Europe. Our focus must be more on recycled materials and their qualities so that raw materials can be kept in the cycle.
More than 500,000 tonnes of end-of-life tyres are generated in Germany every year. What are currently the biggest bottlenecks in the infrastructure for collection, sorting and processing?
At present, the SME sector in Germany is structured in such a way that all tyres generated can be collected, sorted and processed. Our biggest challenge is that the material is currently being exported rather than ending up with responsible companies in the circular economy. We estimate that around 100,000 tonnes are exported annually without proper regulation.
How will the network influence future EU regulations on the circular economy?
We are delighted to be engaging in growing dialogue with EU bodies, which enables us to raise the profile of the circular economy, which is dominated by small and medium-sized enterprises. Our aim is to set the right course at European level as quickly as possible so that companies can work successfully with the materials and keep as many raw materials as possible in the cycle.
Which groundbreaking technologies or business models are currently attracting the most attention?
There are quite a few, and to name just a few, we have companies in the network working on AI-driven solutions for tyre sorting as well as start-ups producing devulcanised materials for the new tyre industry or AI-assisted machines for the professional regrooving of truck tyres.
How important is cross-border cooperation in establishing a sustainable circular economy for tyres across Europe, rather than in isolated national markets?
AZuR started as a German network, but we can now safely say that we have become a European network. We have partners from Italy, the Netherlands, Austria, Ukraine, Estonia and Poland. All these countries face similar challenges as the relevant legislation is often decided at European level and we can achieve very little at national level. We can only take the big steps together in Europe.
How difficult is it to reconcile economic interests within such a diverse ecosystem?
All AZuR partners are united by a shared vision of 100 percent recycling of end-of-life tyres generated in Europe. We know that this is economically viable. However, we also know that we can only tackle the hurdles that are currently preventing us from reaching our goal by working together.
Our target of 100 percent recycling of end-of-life tyres is very realistic and, in our view, can be achieved in the short term with the right measures.
How do you respond to the market’s ongoing concerns regarding the safety, quality and performance of retreaded tyres?
The retreaders currently operating in Germany are industrial retreaders whose quality standards are in no way inferior to those of new tyre manufacturers. Real-world use shows that there are no quality limitations with retreaded tyres. When retreaded, the casings from premium manufacturers offer a quality comparable to that of the original new tyre.
Incidentally, the safety of the technology is demonstrated by retreaders of aircraft tyres as such tyres are retreaded 12 to 14 times and are highly relevant to safety. And retreading is the ideal solution for recycling as it allows the tyre to be used a second and third time as a tyre.
Why has retreading uptake in the passenger car sector remained relatively limited compared to that in the commercial vehicle sector?
One of the major challenges facing retreading in the passenger car sector is the vast variety of sizes, which makes retreading economically unviable. We are constantly seeking dialogue with vehicle manufacturers on this issue.
Furthermore, passenger car tyres are often in use for longer because they are driven less frequently, meaning fewer casings are available for retreading. However, we believe in passenger car tyre retreading, particularly given the growing share of electric vehicles, and are delighted that a retreader in Germany will be relaunching operations in this segment this year.
How important will AI, predictive analytics and sensor-based tyre management become over the next decade?
Smart tyre management is both an economic factor for haulage companies and an environmental one. We know that how a tyre is used has a significant impact on its service life. And at the top of the waste hierarchy is waste prevention. Here, both the new tyre industry and users are called upon to make optimal use of tyres so that they can remain in service for as long as possible.
What would success look like for AZuR in the next five years?
We would have reason to celebrate if we were to achieve the following key objectives in the coming years. The objectives include 40 percent market share for retreaded lorry tyres in Europe, 10 percent market share for retreaded passenger car tyres in Europe, 100 percent recycling of end-of-life tyres in Europe and clear legal regulations governing the use of recycled ELTs.
Epsilon Carbon Doubles Speciality Carbon Capacity To 600,000 TPA With New Karnataka Plant
- By TT News
- September 10, 2026
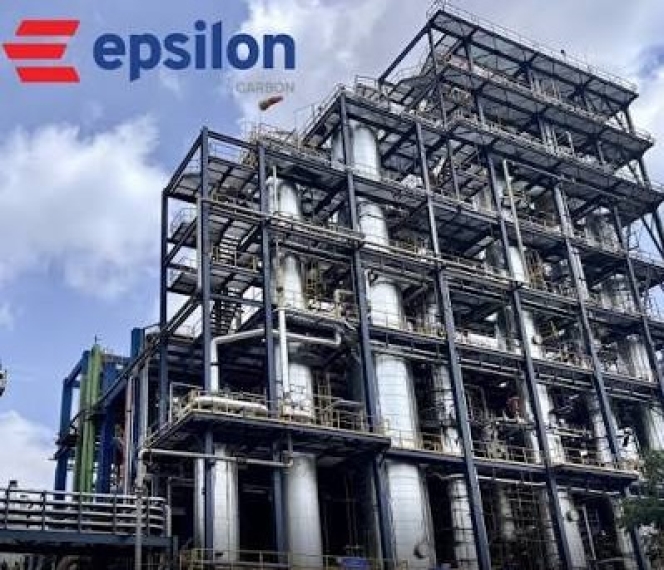
Epsilon Carbon has significantly expanded its manufacturing footprint with the formal activation of a new 300,000-tonne-per-annum speciality carbon plant in Vijayanagar, Karnataka. This latest addition brings the company’s aggregate production capacity in this segment to 600,000 tonnes annually, a development that elevates the firm to a leading position among domestic producers and reinforces India’s broader influence in the international speciality carbon market.
The new installation operates on a fully digitised manufacturing architecture, incorporating real-time process monitoring, automated quality controls and interconnected production systems. Such technological integration is intended to minimise operational variability, maximise throughput and provide overseas buyers with a stable and predictable supply base across multiple product categories.
Output from the Vijayanagar complex will encompass a wide array of coal-tar derivatives, including binder and impregnated pitches, refined naphthalene, anthracene and creosote oils and wash oil. These intermediates find application across a spectrum of heavy and light industries, ranging from primary aluminium and graphite electrode production to tyre compounding, pigment formulation, pharmaceutical synthesis and speciality construction materials.
Looking ahead, the company has outlined a trajectory towards further capacity enhancement, with a proposed integrated facility in Jharsuguda, Odisha, expected to push total speciality carbon output to one million tonnes per annum by the end of the decade. Meanwhile, the Karnataka plant has been configured with closed-loop water management, recycling all treated effluent internally, and derives its entire power requirement from a 17‑megawatt captive unit running on recycled process off-gases. Certifications such as Responsible Care, EcoVadis Silver and SA8000 attest to the company’s adherence to stringent safety, environmental and labour standards.
Gaurav Mathur, Chief Executive Officer, Epsilon Carbon, said, "This expansion reflects India's growing capability to become a global supplier of speciality carbon materials. With 600,000 TPA of Speciality Carbon capacity, we are strengthening supply chain resilience for both domestic industries and international customers, particularly the global aluminium sector. As the world looks to diversify supply chains, Epsilon Carbon is proud to contribute to India's emergence as a reliable, sustainable and globally competitive manufacturing hub."
HS HYOSUNG ADVANCED MATERIALS Showcases Carbon Fibre Innovations At CCE 2026
- By TT News
- September 09, 2026
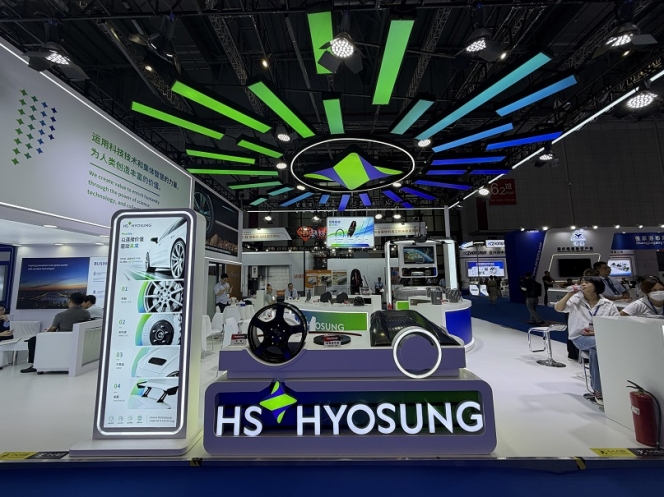
HS HYOSUNG ADVANCED MATERIALS participated in the China Composite Expo 2026 (CCE 2026), held at the National Exhibition and Convention Center in Shanghai from 1 to 3 September. This annual event stands as Asia’s largest specialised exhibition for composite materials, drawing a significant global audience.
The company has been a consistent participant in CCE since 2013, leveraging the expo to progressively reinforce its foothold in the Asian market. At this year’s showcase, the strategic focus was on its portfolio of high-performance carbon fibre products, which are increasingly recognised as essential materials for advanced sectors including energy, mobility and aerospace due to their superior tensile strength and modulus.
Central to the presentation were actual samples of TANSOME, the company’s proprietary carbon fibre brand developed through in-house technologies. The exhibit featured a diverse range of applications, from mobility components like automotive wheels, hoods and brake discs to sporting goods such as hockey sticks and pickleball rackets, as well as high-pressure vessels for hydrogen and oxygen, drones and wire cores.
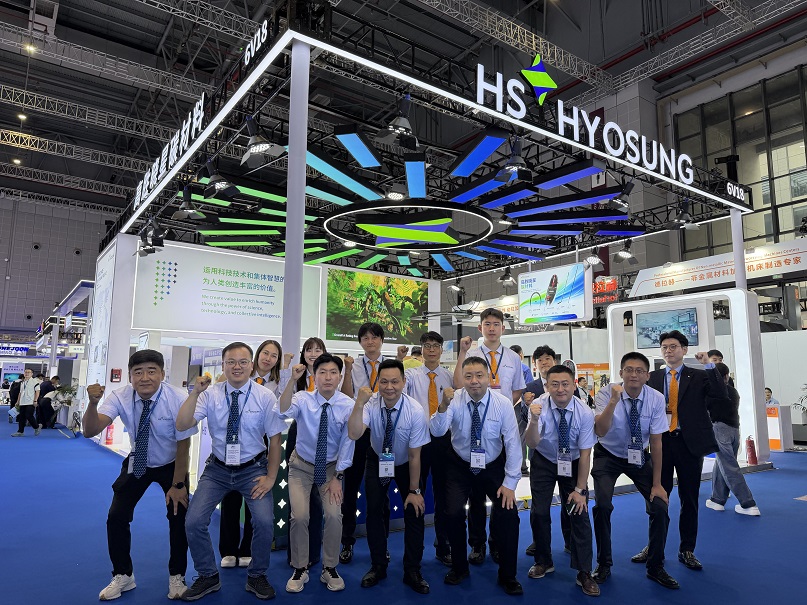
In parallel, HS HYOSUNG ADVANCED MATERIALS emphasised its robust manufacturing capabilities and stable supply chain, supported by production bases in Korea, China and Vietnam. This strategy reinforces its standing as a leading global carbon fibre manufacturer. Notably, the company achieved a milestone in 2011 as the first in Korea to independently develop TANSOME, a material 4 times lighter and 10 times stronger than steel. This was followed by the 2022 launch of H3065, a T-1000-grade fibre with strength exceeding steel by over 14 times, designed for demanding aerospace applications.
Jin Dal Lim, CEO, HS HYOSUNG ADVANCED MATERIALS, said, “This exhibition is an important opportunity to further strengthen strategic partnerships with global customers and demonstrate the outstanding technological capabilities of HS HYOSUNG’s carbon fibre. We will continue to build deeper trust in the global market based on world-class product quality and stable supply capabilities.”
Comments (0)
ADD COMMENT