The 15th Asia Pacific Carbon Black Conference Concludes With Record-Breaking Attendance!
- By Gaurav Nandi
- December 03, 2024
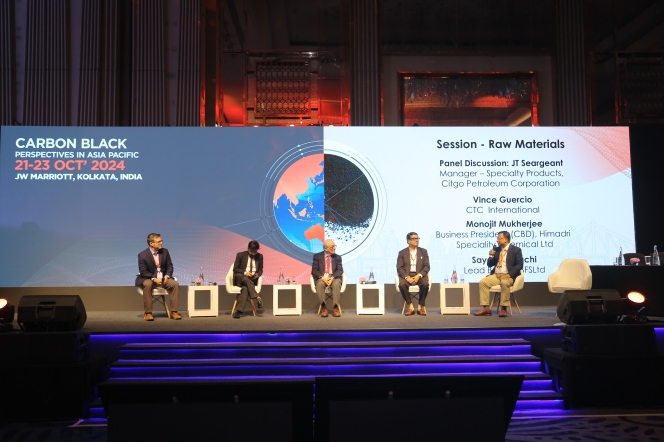
The Asia Pacific Carbon Black Conference 2024 – Perspectives in Asia Pacific, one of the largest and most acknowledged global carbon black industry events, unfolded in Kolkata, India, marking a historic moment for the city. The 15th edition welcomed a record-breaking 252 delegates and featured compelling discussions on the future of the carbon black market, which is projected to reach USD 30.15 billion by 2029. Over three days, industry leaders explored key trends, sustainability efforts and technological innovations, underscoring the sector’s dynamic evolution and the growing importance of India in shaping its future.
The sprawling banquet of a renowned hotel in the City of Joy was attuned to the murmuring of delegates from across the globe when the speaker on the dais invited the International Advisory Committee Chairman Amit Choudhary to address the crowd. With utter excitement, the chairman ascended the stage and opened the 15th Asia Pacific Carbon Black Conference doors to the curious assembly. Over the next three days, the event featured – workshops, intriguing sessions and panel discussions on the global carbon black market, which is slated to reach USD 30.15 Billion by 2029, according to Mordor Intelligence.
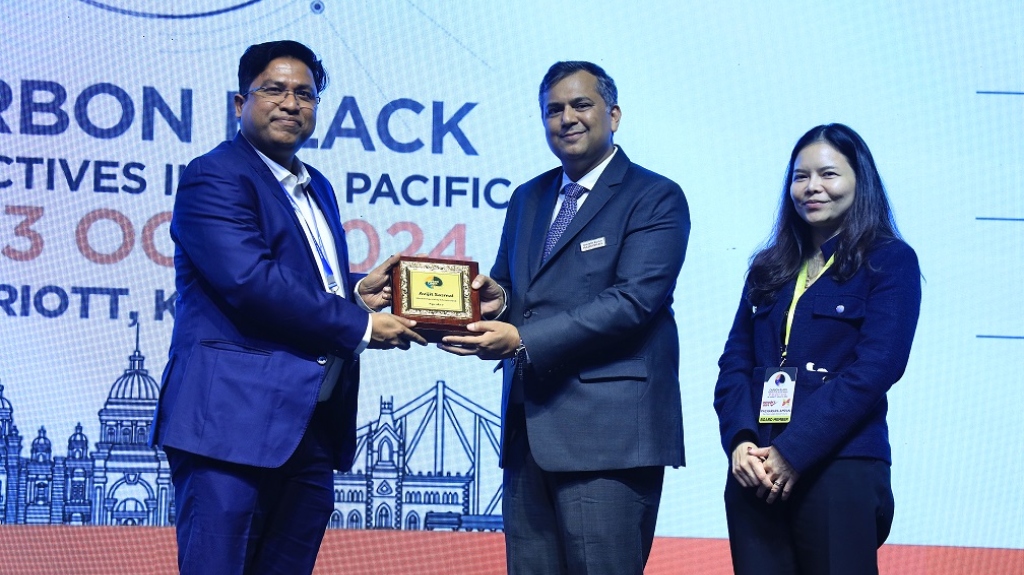
From sessions on the latest trends within the space to the use of recovered carbon black and sustainability issues, the conference was a boiling cauldron of information, coupled with an exhibition spanning different makers and associated suppliers to the industry.
Speaking to Tyre Trends exclusively, Choudhary said, “Key takeaways from the conference were impactful for both participants and delegates, with a record-breaking 252 attendees from around the globe. The exhibition, featuring 36 stalls, marked the largest in the Asia-Pacific region in the event’s 31-year history. The conference kicked off with two workshops on day one, focusing on the technical aspects of carbon black and its applications across the tyre and other industries. About 70 attendees engaged in a robust discussion, addressing numerous technical queries from leading players in the carbon black industry, including Birla Carbon, Tokai Carbon, Himadri Speciality Chemical Ltd, Epsilon, PCBL, and so on.”
He added, “For the first time in its history, the conference featured panel discussions on different topics of the carbon black industry covering marketing, raw materials, application, technology and the future of carbon black, which fostered intense engagement from participants. These sessions provided valuable insights and sparked in-depth discussions, impacting all those who attended.”
Many companies attending the conference were not direct carbon black producers but played key roles in the carbon value chain, either as suppliers to the carbon black industry or as technological collaborators or customers. This diverse representation highlighted the industry’s interconnected nature, with attendees gaining exposure to the latest technologies and processes shaping the sector.
“The conference brought together a global audience, fostering collaboration and providing significant opportunities for local suppliers to engage with emerging technologies. Carbon black production in this region, particularly in India, is experiencing rapid growth.
Companies across the country, from Gujarat and Maharashtra in the west to the east and south, are expanding their operations to meet increasing demand. This growth presents ample opportunities for suppliers of essential equipment and consumables to the carbon black industry, such as refractory manufacturers, bag suppliers and packing material providers. Ultimately, the entire supply chain stands to benefit from the increased collaboration and knowledge exchange fostered at the conference,” averred Choudhary.
Quick view
George Haines, Global Product Director and Avijit Sasmal, Chief Sustainability Officer at Himadri Speciality Chemical Limited, highlighted the carbon black industry’s progress in sustainability and circularity. They emphasised advancements such as the use of recycled pyrolysis oil and reclaimed carbon black and achievements like EcoVadis and ISCC+ certifications. Himadri already achieved the milestones and is maintaining Zero Liquid Discharge (ZLD) across plants. Innovations like LFP Cathode Active Material for EV batteries and renewable energy showcased Himadri’s future readiness. This session set a benchmark for aligning industry practices with global climate goals.
Senior Manager - Technology, K. Arun Kumar, and Manager, Technology and Business Development, Dr. P.M. Sivaram, at CUMI Super Refractories, discussed enhancing reactor life in the carbon black industry through condition monitoring and refractory solutions. They emphasised the need for failure analysis, material characterisation, and data-driven strategies to predict failures, improve productivity, and reduce downtime, ultimately leading to more efficient and sustainable operations in the industry.
The workshop by Himadri Speciality Chemicals Limited Plant Head Kingshuk Bose, on ‘Recent Advancements in Carbon Black Technologies’ provided an overview of carbon black, its applications, and recent technological innovations in its manufacturing processes. He discussed new technologies such as plasma and nanotechnology, which enhance production efficiency and product characteristics. Additionally, AI and machine learning were highlighted to optimise processes, improve quality and predict maintenance needs, ultimately advancing carbon black manufacturing and packaging strategies.
The former Chief Advisor of Research and Development at Apollo Tyres, P K Mohamed, an industry stalwart, addressed the future of the tyre industry, focusing on advancements in carbon black technology in his key note address. He noted that pneumatic tyres, essential for load support, require optimal structures to endure operational pressures. The industry faced megatrends such as mobility, digitisation, electrification, and the shift toward renewable materials. Key customer expectations centre on rolling resistance, traction, durability, and sustainability improvements. Enhancements in carbon black properties, including particle size and surface chemistry, are vital for achieving these goals. The industry’s evolution towards higher sigma levels indicated a commitment to quality and performance, necessitating collaborative efforts in research and development to meet future demands.
Notch Consulting Inc. Founder and President Paul Ita spoke on the outlook for 2024 and highlighted significant developments in the global carbon black and tyre industries. He noted a projected total investment of INR 27.3 billion in new tyre capacity from 2023 to 2028, with Asia, especially China and India, leading in new projects. He also discussed the impacts of EU sanctions on Russian carbon black imports. These sanctions are shifting trade flows, with India emerging as a key supplier to replace Russian volumes. The analysis included production capacity and utilisation trends with a forecast for growth in carbon black production despite current disruptions.
The AGM Strategy at Epsilon Carbon, Sagar Mathur, noted that geopolitical shifts, rapid urbanisation, climate change, sustainability, and technological advancements are shaping the future of the carbon black industry. Key trends included the growing demand for Electric Vehicle (EV) tyres, increased focus on circularity and recycling technologies, and the need for advanced speciality products. He highlighted that urbanisation is expected to strain resources while geopolitical conflicts are reshaping supply chains. The industry must adapt to these changes while addressing environmental concerns, leading to new product development, particularly in sustainable materials.
Vice President of Sales and Marketing (CBD), Kane Hanneke and Vice President of Business Development and Sales (CBD), Surge Klunder, at Himadri Specialty Chemical Ltd, focused on the current demand and supply dynamics of carbon black in North America and the European Union as of October 2024. In their presentations, they highlighted key economic indicators such as GDP growth, inflation, and the Manufacturing Purchasing Managers’ Index (PMI), while discussing challenges faced by domestic producers, including import duties, geopolitical tensions, and rising oil costs. Kane also mentioned a notable production increase among leading carbon black producers, particularly in China and India, and addressed the impact of new tariffs on Mexican imports.
Executive Vice-President and Regional Head of Sales and Marketing at Birla Carbon, Shashank Awasthi, discussed the dynamics of the carbon black market in Asia and Europe with a focus on growth plans and regional capacities. He highlighted that China dominates the market with a capacity share of 47 percent and a demand share of 37 percent. He also covered competition in India, where local producers faced challenges from imports, particularly from China, Korea, and Russia. His analysis indicated a projected CAGR of 5 percent for the Southeast Asia carbon black market from 2022 to 2027, driven by rising disposable incomes. It increased automotive production, with Asia accounting for approximately 60 percent of global automobile manufacturing.
The presentation by Zircoa Managing Director Thomas Bohm focused on the role of zirconia refractories in enhancing reactor performance during carbon black production. Zirconia, a unique ceramic material, offers exceptional properties such as high thermal resistance, lower thermal conductivity, and erosion resistance, making it suitable for high-temperature applications in reactors. The advantages of zirconia include increased reactor efficiency, improved product yields, and the ability to withstand aggressive process gases. However, challenges such as degradation from thermal shock and alkali attacks were noted, emphasising the importance of proper alignment and operational practices to maximise the lifespan of zirconia linings.
In his virtual keynote session, Zhu Zilong, deputy director of design at Doright, discussed the emerging supply trends in equipment manufacturing, particularly focusing on the shift from individual equipment supply to comprehensive equipment packages.
The landmark event saw the attendance of dignitaries and industry stalwarts, including the Chief Secretary to the Government of West Bengal, Dr Manoj Pant, Himadri Speciality Managing Director Anurag Choudhary, Tokai Carbon President Hagime Hagasaka, Group Country Head, Aditya Birla Group Thailand, and Chief Expansion Officer Birla Carbon Asia, Sanjeev Sood, among others.
Key Speakers included Aditya Birla Group’s Chief Sustainability Officer Deeksha Vats, Former President at ALSTOM Power Energy Recovery CP Natarajan, Vidhitech Solutions Founder Vinod Taneja, ABG Trading President John Kennelly, Senior Manager Research and Development of Compound Development at CEAT Limited Dr Pranab Dey, Head - Projects Business at Thermax Limited Naveen Sadhu and Rathi Group Director Ravi Rathi among others.
The event was attended by delegates from leading carbon black producers, such as Thai Tokai Carbon Product Company Limited, Hyundai OCI, Aegean First Company, Zircoa Inc., Phillips Carbon Black Limited, CITGO Corp and others.
Curtain Call
Amit Choudhary commented about the conference, “Conferences like this serve as crucial platforms for advancing technological progress in the industry. They provide insights into global trends, revealing which players are exploring new technologies and how different governments are approaching industry expectations. These events create an opportunity for stakeholders to understand evolving needs as well as the requirements of end customers.”
He added, “For instance, during our recent conference, several customers presented compelling insights, with both in-person and online interactions offering a deeper understanding of the tyre industry’s future. The rise of EVs is a key development demanding a shift in tyre technology and manufacturing processes. Current tyres are general-purpose, but as EV adoption accelerates, specialised tyres will become necessary. In the near future, we will see the emergence of EV-specific tyres alongside innovations in related non-tyre markets.”
He also noted that India, with its significant market share, is poised for substantial growth. Established markets in the US and Europe are facing challenges with plant closures and shifting demands. The ongoing geopolitical landscape, including tensions in China and Russia, is influencing market dynamics. However, India remains in a favourable position for investment and is set to experience impressive growth in the sector.
Looking ahead, the next conference is set to take place in 2026.
Competitive Aggression
- By Gaurav Nandi
- October 15, 2026
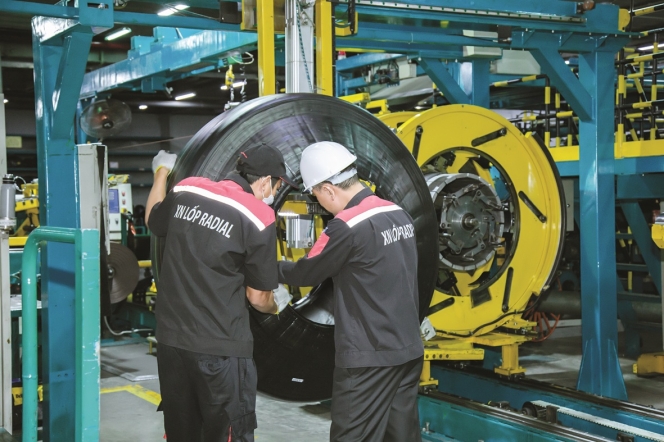
Vietnam’s growing role as a global tyre manufacturing base is creating new opportunities for domestic producers, but breaking into established international markets remains difficult. Da Nang Rubber Joint Stock Company is expanding exports and production capacity while confronting larger Chinese rivals on price and established global manufacturers on technology, distribution and brand strength. General Director Le Hoang Khanh Nhut tells Tyre Trends that competing globally will require Vietnamese manufacturers to move beyond cost advantages and demonstrate quality, operating efficiency and long-term customer value.
Southeast Asian tyre manufacturers have evolved as an aggressive competitor in the global tyre race. Tyre makers from China, Vietnam, India, Thailand etc. are constantly competing for a share of the bigger pie. While one nations tyre manufacturer competes on price advantage, another competes on quality.
The tyre manufacturing scene in Vietnam resonates quality and pricing in the global stage. But that is not the end of the story. On one hand, many manufacturers from other countries are leveraging the strategical importance of Vietnam for pushing products into international markets.
And on the other hand, trade tariffs and anti-dumping duties are creating hurdles for such companies. “Trade defence measures, anti-dumping actions, rules of origin and tariff changes have become ongoing factors in export management,” said Da Nang Rubber Joint Stock Company (DRC) General Director Le Hoang Khanh Nhut during an exclusive interaction with Tyre Trends magazine.
He confidently stated that DRC closely monitors each market to select appropriate products, pricing structures, distribution partners and production plans while ensuring that origin documentation, technical compliance and trade compliance are properly standardised.
“Trade barriers can increase costs and risks, but they can also create opportunities when customers seek to diversify their supply sources beyond a single country. The pre-requisite is that Vietnamese companies maintain transparency regarding origin, control their supply chains and retain genuine competitiveness,” he quipped.
Explaining the current situation within the country’s broader market economics, a confident Nhut averred that Vietnam’s expanding infrastructure, logistics network and export connectivity are creating favourable conditions for tyre manufacturers operating in the country.
He added that the country was investing heavily in highways, transportation and logistics infrastructure. That development is supporting both domestic demand and the country’s ambitions to become a manufacturing and distribution hub for global markets.
For DRC, the expansion of Vietnamese tyre manufacturers into global markets will depend less on competing solely on price and more on leveraging manufacturing experience and product quality.
Asked how Vietnamese manufacturers could compete with Chinese tyre makers, which often operate with larger research and development budgets, Nhut said, “The strategy is to focus on experience and quality rather than entering a price-led competition. We don’t follow the price competitively like Chinese companies.”
STRATEGIC PLACEMENT
International markets, especially Europe and America, are crucial to Vietnamese tyre manufacturers including DRC. The company states that the US is an established and important export market.
In April 2024, DRC signed an export agreement with Oceanside One Trading covering Brazil and the US with the stated aim of increasing exports to those markets.
Europe is strategically important but not one of its mature core markets yet. The company’s 2024 annual report explicitly states that it aims to increase its market share in Europe.
Nonetheless, the local market assumes a similar importance for the company. “The domestic market remains a strategic foundation for us. It is where the brand has been built over several decades. We have an extensive distribution network here and the market helps us maintain a balanced production volume,” said Nhut.
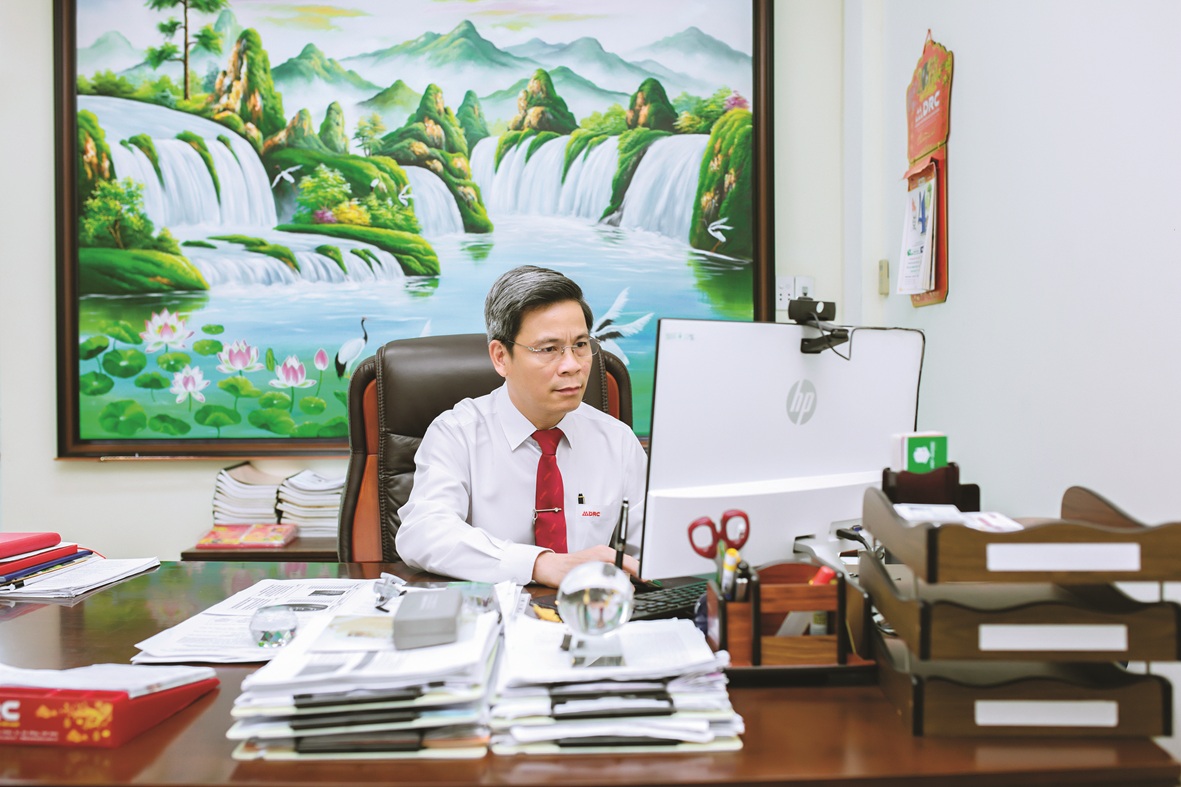 Le Hoang Khanh Nhut, General Director, Da Nang Rubber Joint Stock Company (DRC)
However, the challenges include periods of weaker purchasing power, strong competition from imported products and FDI-based companies and pricing pressure. “Unlike many export markets, Vietnam has a fragmented distribution structure; customers are price-sensitive but also place strong importance on durability, product availability and warranty response time,” explained Nhut.
On the broader spectrum of market-linked business advantages, the country has become a manufacturing base for many international tyre manufacturers. “Vietnam has several practical advantages including a favourable location for exports, access to many markets through FTAs, an increasingly skilled technical workforce and a developing supporting-industry ecosystem,” stated Nhut.
DRC perceives these advantages are complemented by accumulated manufacturing experience, a domestic brand, an established workforce and a production management system that is being modernised.
“However, we still face disadvantages in terms of economies of scale, the degree of self-sufficiency in strategic raw materials, logistics costs, supply-chain depth and resources available for foundational technologies compared with China, Thailand, Indonesia or India. These areas need to be addressed through focused investment and supply-chain integration,” he noted.
INTERNATIONAL TUSSLE
DRC’s manufacturing operations are based in Da Nang, where it operates separate facilities for different tyre categories. Nhut cited production covering passenger car tyres, motorcycle and bicycle tyres, agricultural tyres, OTR products and other categories.
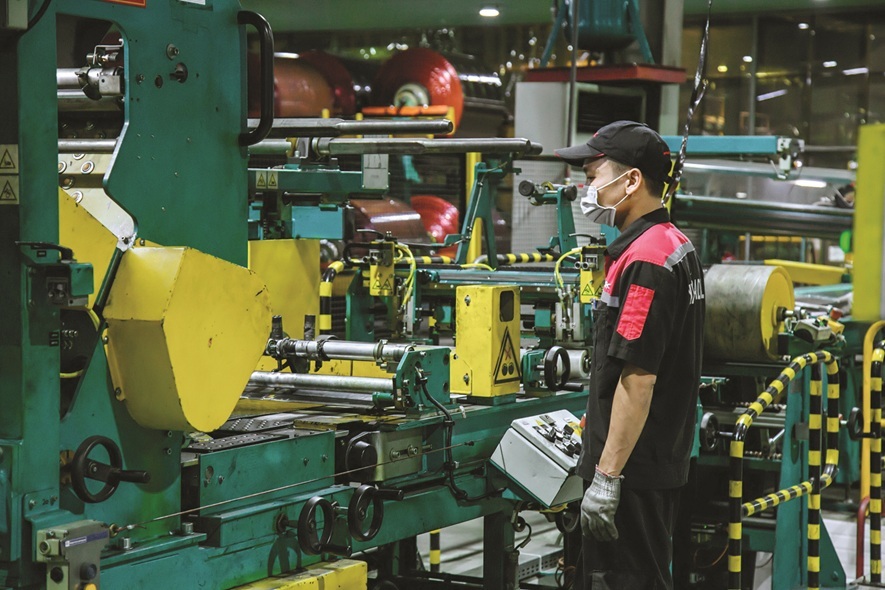
The chief executive estimated its overall production at around five million tyres. And in recent years, its international business has seen clear growth in both scale and geographical reach.
By the end of 2024, export turnover had exceeded USD 100 million, and its products are currently present in more than 50 countries and territories including markets with high standards such as the US, Europe, Japan, South Korea and Brazil.
“Our focus remains on strengthening markets where we already have a solid foundation, particularly in the Americas and developed markets, while selectively expanding into regions with significant room for growth,” contended Nhut.
He added that demand is shifting towards greater emphasis on consistent quality, durability, operational efficiency, reliable supply and technical compliance. Therefore, exporting is no longer simply about selling products but about building the capability to serve markets over the long term.
Nonetheless, Chinese tyre companies are a much stronger competitor in international markets for Vietnamese counterparts. Explaining how DRC navigates the challenge of competing head-to-head with Chinese tyre markets, Nhut said, “The expansion of Chinese tyres has intensified price competition in the replacement market, particularly in mainstream segments. This has created direct pressure on selling prices and margins across the industry.”
“We do not compete solely on price and focus on consistent quality, durability, technical service and real-world operating efficiency to retain customers. The market has indeed become more challenging, but it also creates opportunities for manufacturers that demonstrate product lifecycle value, consistently meet delivery commitments and reliable after-sales support,” he added.
GLOBAL STRONGHOLD
According to Nhut, DRC’s strongest international growth opportunities are in segments where it already has capabilities and credibility that include radial truck and bus tyres, industrial and agricultural tyres and speciality tyres.
“The expansion of radial truck tyre capacity to one million tyres per year is an important step in increasing our ability to serve the market. At the same time, we need to continue shifting our product mix towards higher-value products with higher technical requirements, durability and specialisation,” he added.
Product lines for next-generation vehicles and technical rubber products are also focus areas for the company. It also does not consider expanding the product portfolio to be an objective in itself. It must be aligned with research and developmental capabilities, investment efficiency and market demand.
The investment sentiment within the country’s tyre industry is also seeing heightened demand. It has attracted significant investment and substantially increased production capacity.
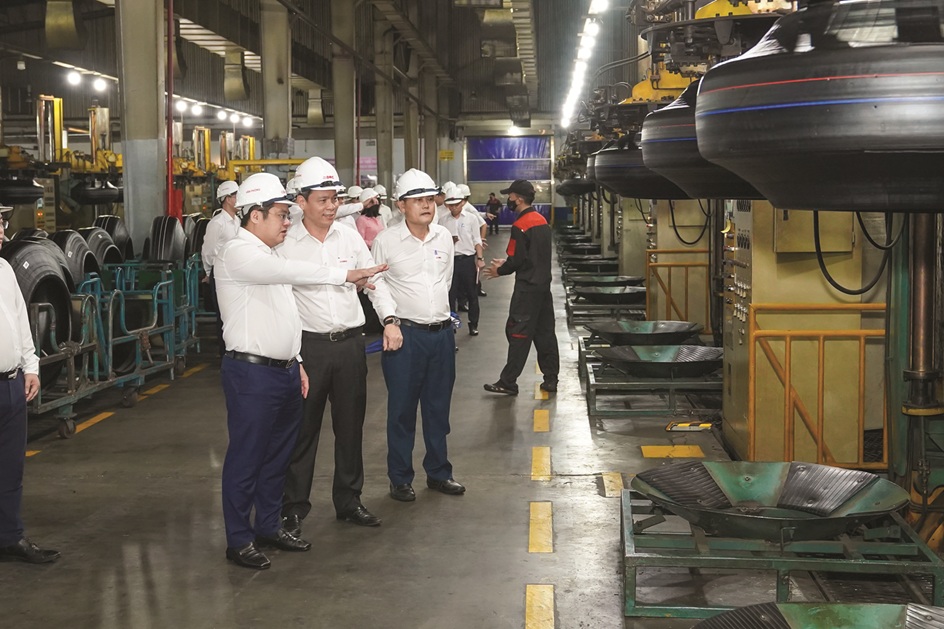 But the additional investment in Vietnam’s tyre industry is both an opportunity and a source of pressure, said Nhut.
“The opportunity lies in improvements to the supply chain, technical workforce, logistics services and Vietnam’s attractiveness as a manufacturing base. The pressure comes from greater competition for skilled labour, raw materials, customers and quality standards,” he added.
The company, however, views the current situation as a driving force to improve productivity, enhance quality and penetrate its own brand deeper into markets.
And to become a major name in the global tyre market, the company needs to shift from a mindset of exporting products to building a brand and the capability to serve international markets, contended an excited Nhut.
“The focus should be on maintaining consistent quality; investing in research and development; green manufacturing technologies; developing higher value-added segments; building sufficiently strong distribution and after-sales networks in key markets; applying international standards in
quality, ESG, trade compliance and data management and strengthening global human resources capabilities,” added the executive.
Expanding radial production capacity is necessary, but ultimately, success lies in DRC’s ability to build long-term trust in quality, operating efficiency and responsibility towards customers worldwide, noted the executive.
PERSISTENT HURDLES
The biggest challenge for DRC is competing with groups that have significantly greater scale, larger research and development budgets, distribution networks and purchasing power for raw materials.
According to Nhut, Chinese companies have advantages in terms of price and speed. Japanese, Korean and European companies are strong in technology, branding and OEM relationships, while Indian companies have scale advantages in certain segments.
He further noted that DRC’s strengths lie in its longstanding experience in radial truck, bias, agricultural and speciality tyres; its flexibility in responding to market needs; proven quality in many demanding markets and manufacturing base in Vietnam.
However, scale remains a limitation when it comes to long-term research and development investment, rapidly expanding after-sales networks, maintaining regional inventories and increasing global brand recognition.
“We cannot compete with multi-national groups in terms of the scale of research and development spending. Therefore, our approach is to focus resources on issues that have a direct impact on customers and production efficiency,” explained Nhut.
He added, “Our priorities include tyre structure and rubber compound design to improve durability, reduce heat generation, enhance load-carrying capability and improve fuel efficiency. Optimisation of radial products, development of products for emerging needs such as electric vehicles, high-speed tyres and specialty products as well as automation, digitalisation, traceability and green manufacturing are also priorities.”
The company also places strong emphasis on strengthening its engineering team, technical cooperation and shortening the cycle from testing to commercialisation.
Customers are increasingly evaluating tyres based on total cost of ownership rather than simply the initial purchase price. And to convince international fleets and distributors, DRC needs to speak through operating data rather than relying solely on catalogues.
“We are increasing real-world testing and monitoring mileage, wear, fuel consumption, incident rates and reusability or recyclability depending on the product line. Based on this data, we work with distributors to provide technical advice, clear warranty policies and rapid feedback,” stated Nhut.
The objective of the company is to help its customers see a product with a reasonable purchase price that lasts longer, operates more consistently and reduces vehicle downtime to create greater value over its entire lifecycle.
The company has a retreading facility and stated that some casings can be retreaded two or three times.
FORWARD PATH
Nhut expects Southeast Asian tyre manufacturers to continue expanding their presence in global markets.
“Over the next 3–5 years, significant room for growth lies in replacement markets with demand for radial truck tyres, agricultural, industrial and speciality tyres as well as among customers seeking a stable and diversified source of supply outside traditional manufacturing centres,” said Nhut.
The Americas, selected European markets, the Middle East, Africa and Latin America all need to be approached selectively based on trade conditions and service capabilities, he added.
The factors limiting faster expansion include the need to build distribution networks, inventory, after-sales support and local technical certifications together with working capital requirements, foreign-exchange risks, logistics and trade barriers.
“These are long-term investments and cannot be pursued at the expense of sustainable growth,” noted Nhut.
Asked how manufacturers from Vietnam and other Asian markets could position themselves against established European tyre makers, DRC said its focus would be on expanding its market presence rather than retreating from competition with larger international manufacturers.
The current situation in Vietnam reflects a broader shift in the tyre manufacturing landscape, with Asian producers increasingly seeking opportunities in overseas markets while established manufacturers face changing cost structures and production strategies.
Vietnam’s emergence as a competitive tyre manufacturing base gives DRC a platform for international expansion, but geography, trade access and manufacturing costs alone will not secure a global stronghold.
The bigger test is whether the company can translate rising capacity and decades of production experience into stronger technology, distribution, after-sales support and brand recognition.
As competition intensifies and trade barriers multiply, DRC’s global ambitions will increasingly depend on proving lifecycle value rather than simply offering another competitively priced alternative from Asia.
HF Group Receives Continental Supplier Award For Service And Maintenance
- By TT News
- October 14, 2026
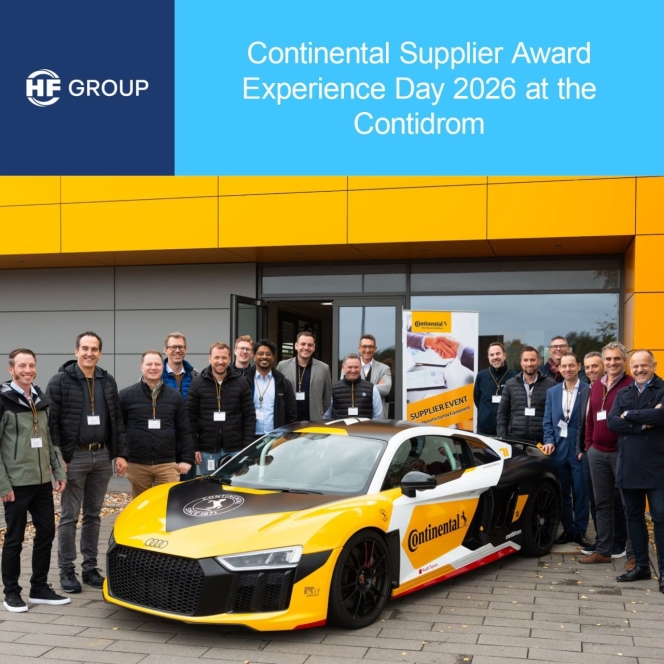
HF Group has received Continental’s Supplier Award for Tyre Manufacturing Equipment 2025 in the Service, Maintenance & Repair category, recognising its work delivered during the year.
The award acknowledges the contribution of HF Group’s mixing and curing teams across multiple deliveries, service assignments and engineering projects undertaken with Continental in 2025.
To mark the recognition, Continental invited the award winners to an Experience Day at its Contidrom test facility near Hanover on recently. The event gave attendees an opportunity to experience Continental’s tyre technology and drive on the test track.
HF Group was represented by André Arends, Garlef Dombrowski, Florian Droege and Peter Hummel.
The company thanked Continental for the award and recognised the expertise and collaboration of its teams in delivering the work.
Hidden Cost In Tyre Plants: How The Rubber Moves
- By Gaurav Nandi
- October 14, 2026
Interroll’s Gianmichele Piciocco argues that some of the largest efficiency gains in tyre manufacturing lie in the interfaces between machines, not only in the machines themselves.
Tyre manufacturers invest heavily in the best building machines and the fastest curing presses. The systems that connect them, however, are often specified late, inherited from earlier projects and seldom revisited, according to Gianmichele Piciocco, Global Strategic Business Development Manager at Interroll.
“Material flow is the backbone of the entire tyre industry,” Piciocco tells Tyre Trends. In his experience, engineers select and position process equipment first, and transport follows. The consequences emerge later, in energy consumption, maintenance stoppages and the cost of expansion. He argues that ‘we have always done it this way’ becomes a design constraint in its own right once technology, product mix, energy costs and safety expectations have changed. The examples that follow point to two closely connected areas: system optimisation during design and expansion, and lifecycle optimisation during operation.
THE LAYOUT TRAP
Piciocco says the pattern is consistent across the tyre manufacturers he advises. “In many cases, the layout initially proposed does not fully match what is ultimately implemented, often to contain the initial investment,” he says. Soon after start-up, plants may find that they need more buffer capacity, or that future expansion was not fully considered. With no floor space left, the remedy for material flow is often inclines, declines and additional levels, which can significantly increase costs.
 The alternative is far cheaper if raised early. “At the design stage, and with possible expansion in mind, it is worth asking whether small changes in machine positioning could support more effective and flexible material flow,” he says.
The issue is especially relevant in India, where sustained market growth does not always mean new greenfield plants. Expansion often happens inside operating sites, where new capacity must coexist with several generations of equipment from multiple vendors. Without a common architectural logic, each extension can add another component family, control standard and maintenance practice, increasing complexity and the potential for integration and compatibility problems.
REOPENING THE BELT QUESTION
Green-tyre transfer illustrates how convention hardens into constraint. Uncured rubber is soft and contamination-sensitive, and belt conveyors have long been the default because a continuous surface supports the tyre and certified belt materials address contamination. Piciocco does not dismiss that logic. He argues it should no longer be treated as absolute.
Left on widely spaced rollers, a green tyre can begin to deform during relatively short stops, and contact with the wrong material can degrade quality after curing. One approach being evaluated by Interroll combines closely spaced rollers, software that keeps them ‘skating’ when the line stops and transfer materials selected to meet contamination requirements. Where a roller solution suits the application, he says, component cost can be materially lower than a belt’s. Because a belt is a continuous element, maintenance work can also take longer and be more complex.
The larger benefit, he argues, is commonality. The same families of rollers, drives and transfer modules can serve both pre-cure and post-cure sections, reducing the spare parts a plant holds and the skills its teams must learn. “Who is interested in saving money in the life cycle of the plant? The user,” he says.
SAVING ENERGY BY DESIGN
Piciocco says moving from conventional 400-volt drive systems to zoned 24/48-volt roller conveyors can reduce energy use, with savings of up to 50 percent in some applications. The low-voltage architecture can also simplify installation and maintenance and reduce exposure to hazardous voltages at machine level, subject to applicable safety standards. The advantage, he stresses, comes chiefly from the on-demand, zoned operating principle, in which only the zones a product needs are active, rather than from voltage alone.
Another example concerns a leading tyre producer that wanted a more compact layout within an existing plant while retaining sufficient buffer capacity and scope for future expansion. The initial conveyor concept required several accumulation loops, curves, inclines and declines, making both engineering and installation relatively complex.
“Working together, we proposed a solution comprising a motorised ascending spiral, an overhead bridge and a gravity spiral for the descent,” Piciocco says. “Each spiral has a footprint of roughly three metres in diameter. At a height of about 7.5 metres, the motorised spiral can provide buffer capacity for approximately 25 to 40 tyres, depending on their dimensions.”
The configuration provided the required buffer in a very compact footprint, with fewer powered components and a cleaner, more modular installation. Its cost was in line with, or slightly above, the conventional solution. Piciocco says the question he put to the customer’s technology director was simple: “Are you thinking about today, or the next 10 years?”
GROWING WITHOUT REBUILDING
A brownfield expansion is not simply a matter of adding more metres of conveyor. New sections must fit existing space, controls and maintenance organisation while the plant keeps running.
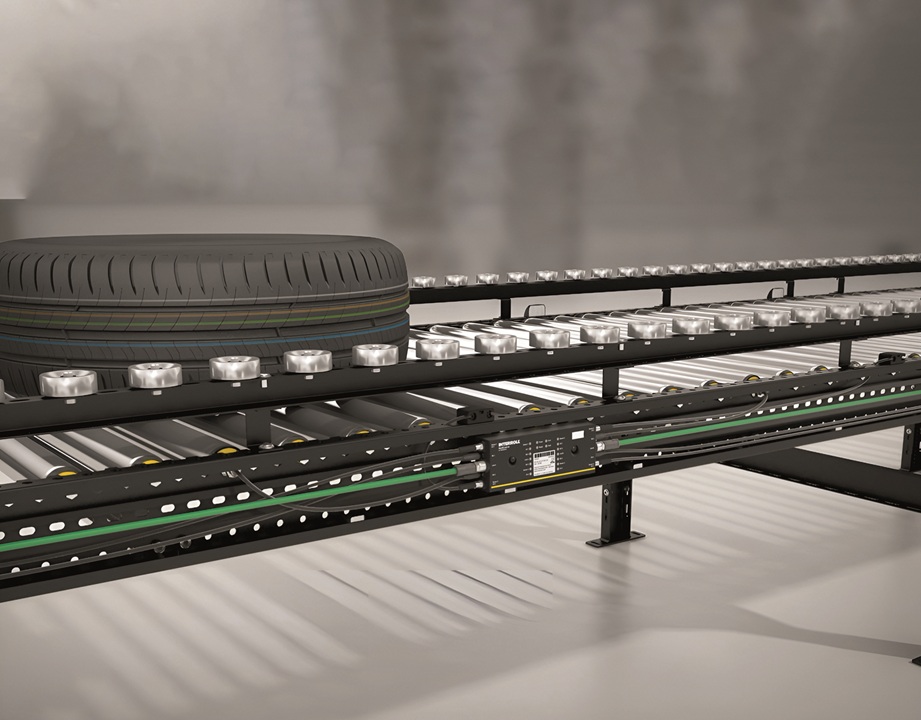
Interroll’s modular platforms, including the MCP range, are built from standard modules. RollerDrive EC5000 units, managed by MultiControl electronics, form a highly scalable and energy-efficient material handling system.
In a conventional centralised architecture, adding zones can require additional I/O, cabling and software changes. In a decentralised system, expansion means adding a module and an Ethernet connection. Independently controlled zones can also absorb small cycle-time differences and micro-stoppages without passing every interruption down the line. Upgrades follow the same logic. The 24-volt EC5000 versions rated at 20 and 35 watts with Analogue Interface (AI) can be used as replacements for the earlier EC310, supporting a more straightforward maintenance approach and the extension of existing installations.
ROUTING WITHOUT OVER-ENGINEERING
Not every route variation calls for a sorter. When tyres must be directed to testing, quality inspection, rework or the next process, Interroll’s position is that a modular conveyor backbone with targeted transfers and diverters often gives a better balance of performance, footprint and cost than a sorter built for distribution logistics. Further downstream, particularly after warehousing, higher volumes and more destinations can justify a dedicated sorter such as the company’s MC-S range.
Piciocco’s warehouse example shows the risk of getting this wrong. A large operator that stacks and stores tyres with considerable automation then needs a separate, costly sorting system to retrieve and route them. In this part of the process, he says, a solution such as Interroll’s MC-S can provide the required throughput with a more efficient layout and a significantly smaller footprint.
CONTINUITY INTO DOWNSTREAM HANDLING
Where load and duty allow, the same architecture can extend past the individual tyre. A 24/48-volt modular pallet conveyor, the MPP platform, can handle a load of up to 500 kilogrammes per metre while retaining decentralised control and zero-pressure accumulation. Rollers of 60 millimetres in diameter allow a closer pitch and more support points, which, after application validation, can reduce vertical undulation when handling tyre stacks.
Piciocco is careful not to make continuity a dogma. Above the platform’s operating envelope, robust 400-volt heavy-duty conveyors remain the correct choice.
FROM REACTION TO PLANNING
Maintenance is where Piciocco sees the most overlooked cost. When total cost of ownership and plant availability are considered, he says, maintenance and stoppage-related costs can account for around 10 to 15 percent of the overall cost associated with material flow in some applications, including labour, spare-parts inventory and lost production during downtime. “Maintenance is often treated as something that simply happens. It should not be. Much of it can be avoided,” he says.
Connected drives, such as the RollerDrive EC5000 BI with MultiControl, make more than 100 parameters available, including operating hours, cycle counts, temperature, system status and error type. If the torque required by a motor rises progressively, the system can flag an abnormal trend before it develops into a stoppage and give the maintenance team a stronger basis for planning an inspection.
Without that information, a failed motor can cause a prolonged stoppage while crews identify the source and check whether the spare part is available. With an early warning, maintenance can schedule the intervention; for an accessible RollerDrive with the spare available, replacement can take less than an hour. Piciocco calls this preventive rather than predictive maintenance. The data does not replace maintenance expertise, but it gives teams a stronger factual basis for decisions, and standard components make diagnostics and training common across the plant.
GLOBAL STANDARDS, LOCAL EXECUTION
A shared catalogue alone does not make a standard, Piciocco says. It also needs consistent selection criteria, spare-parts strategies and support after start-up. Interroll has production, engineering and service capabilities across the world’s main industrial regions, allowing global standards to be supported by local execution. Its life-cycle offering includes structured maintenance programmes, dedicated stock of critical components, periodic audits and staff training, scaled to how critical the application is.
He applies the same logic across markets. Using a smartphone as an analogy, Piciocco says the same platform can be used in a basic configuration or with more advanced functionality, depending on a plant’s needs and technological maturity. A manufacturer can therefore retain common components, diagnostics and training across sites while adapting the level of automation to local conditions.
That flexibility extends to how far automation should go. Speaking for himself, not Interroll, Piciocco says not every producer needs a dark factory. The appropriate level of automation depends on volumes, product mix, process maturity and available skills. “If people do not understand how the technology works, you can have the best technology in the world, but it will not be used properly and may even become a limitation,” he says.
REAL ISSUE
Asked what single mindset shift the industry needs, Piciocco did not hesitate. “Interface,” he says. “The machines are already quite optimised. The problem is how we serve the machine.” As individual machines become increasingly optimised, the interfaces between them play a growing role in improving productivity, simplifying maintenance, reducing energy consumption and enabling future expansion.
“Material flow should not be the last part of the engineering process,” he adds. “If it is considered earlier, we can contribute to a solution that supports optimisation of the entire plant.”
ATIRE Appoints Thierry Miche As Director Of Oem And Product
- By TT News
- October 13, 2026
ATIRE, a leading Sri Lankan Solid tyre maker, has appointed Thierry Miche as director of OEM and product, effective September 2026, bringing more than 25 years of experience in the global tyre and mobility industry to the role.
At ATIRE, Miche will lead the company's OEM and product activities, focusing on portfolio development, OEM relationships and expansion into new technical and commercial markets globally.
Miche joins from Michelin, where he spent 26 years in senior product and operational leadership positions, including roles at Solideal and Camso before their integration into the French group.
His most recent position was product Management Director for Beyond Road, with global strategic and operational responsibility for the product portfolio. He led teams across Belgium, Canada, France and the US, working with research and development, industrialisation, original equipment manufacturer (OEM) and aftermarket sales, and supply chain functions.
Previously, Miche was Product Line Executive Director For material handling, overseeing the global product platform and holding full profit and loss responsibility for three manufacturing sites in Belgium, Germany and the US. He also led global research and development teams in Belgium and Sri Lanka.
His career has spanned product management and engineering, technical support, warranty management, quality assurance and systems. The experience covers the development and delivery of products across engineering, industrialisation, validation, sales and supply chain operations.
Comments (0)
ADD COMMENT